
3 LPA Salary in India: In-Hand Pay, Deductions, and Complete Breakdown
Securing a job offer with a ₹3 Lakh Per Annum (LPA) compensation package represents an exciting career milestone, particularly for fresh graduates entering the corporate workforce. Mathematically, dividing an annual package of ₹3,00,000 by 12 months yields a precise monthly figure of ₹25,000. However, the final liquid cash credited to your bank account on payday rarely matches this exact mathematical calculation.
Employers design salary structures using multiple interconnected components, including mandatory provident fund contributions, state-level taxes, and corporate insurance premiums. These specific allocations directly reduce your monthly cash flow. Understanding the precise mechanics behind your 3 LPA in hand salary empowers you to negotiate better terms with human resources, construct a realistic monthly budget, and set accurate financial expectations before signing your employment contract.
This comprehensive guide breaks down the structural differences between Cost to Company (CTC) and take-home pay, details the standard statutory deductions, explores the latest tax implications, and provides actionable strategies to accelerate your long-term income growth.
Decoding the Salary Jargon: CTC, Gross, and Take-Home Pay
Corporate human resource departments frequently utilize specialized payroll terminology in offer letters. Separating these three distinct pillars clarifies exactly how much money you will earn and retain.
- Cost to Company (CTC): This overarching figure represents the absolute maximum financial expense an employer incurs to hire, train, and retain you for one year. The CTC bundles your direct basic salary, the employer’s matching provident fund (EPF) contributions, medical insurance premiums, variable performance bonuses, and annual gratuity provisions into one consolidated headline number.
- Gross Salary: This metric denotes your actual monthly pay before the payroll department deducts your personal taxes and statutory contributions. It strips away the employer’s distinct PF share and long-term retention benefits like gratuity, offering a much clearer picture of your base operational earnings.
- In-Hand Salary (Take-Home Pay): This represents the final liquid cash transferred directly into your savings account. Subtracting your personal employee deductions (like your EPF share and professional tax) from the gross salary leaves you with this exact, spendable amount.
Statutory Deductions Impacting Your Monthly Credit
Several mandatory and voluntary deductions shrink your 3 lakh salary per month equivalent. Recognizing these outflows prevents unpleasant surprises when you receive your first payslip.
Employee Provident Fund (EPF)
The Indian government mandates structured retirement savings for eligible corporate employees. The payroll team automatically deducts 12% of your basic salary every month and deposits it directly into your official EPF account. For example, if your basic salary sits at ₹12,500, you contribute ₹1,500 monthly. While this deduction reduces your immediate cash liquidity, the money remains entirely yours. It earns compounding, tax-free interest annually, building a powerful financial safety net for your retirement.
Professional Tax
State governments levy a distinct professional tax on earning individuals to fund local civic infrastructure. The exact deduction fluctuates based on your specific work location and designated income bracket. Working in highly commercialized states like Maharashtra, Karnataka, or Gujarat typically incurs a modest monthly professional tax deduction, slightly lowering your final take-home pay.
Income Tax Liabilities
For the financial year 2026-27, the government overhauled the new tax regime to provide massive relief to entry-level professionals. The updated framework completely exempts total annual income up to ₹4 lakh from basic taxation, alongside offering a robust rebate mechanism for taxable income reaching up to ₹12 lakh. Consequently, earning a standard 3 LPA CTC generates absolute zero income tax liability. You retain your entire income free from Tax Deducted at Source (TDS), assuming you possess no other significant taxable income streams from external investments or freelance operations.
Estimated 3 LPA Monthly Salary Breakdown
Companies utilize drastically different mathematical formulas to construct salary packages. The following tabular breakdown illustrates a highly standard corporate structure where the employer excludes their specific PF contribution from the ₹25,000 monthly gross figure.
| Salary Component | Monthly Allocation | Annual Allocation |
| Basic Salary | ₹12,500 | ₹1,50,000 |
| House Rent Allowance (HRA) | ₹5,000 | ₹60,000 |
| Other Allowances / Special Pay | ₹7,500 | ₹90,000 |
| Gross Monthly Salary | ₹25,000 | ₹3,00,000 |
| Employee PF Deduction (12%) | -₹1,500 | -₹18,000 |
| Estimated Income Tax | ₹0 | ₹0 |
| Approximate In-Hand Salary | ₹23,500 | ₹2,82,000 |
Note: If a specific employer strictly embeds their own 12% matching PF contribution inside the ₹3 lakh CTC limit, your gross salary shrinks accordingly, pushing your final take-home pay closer to the ₹21,500 to ₹22,000 range. Always demand a detailed numerical breakdown before accepting an offer.
Hidden CTC Components to Verify Before Signing
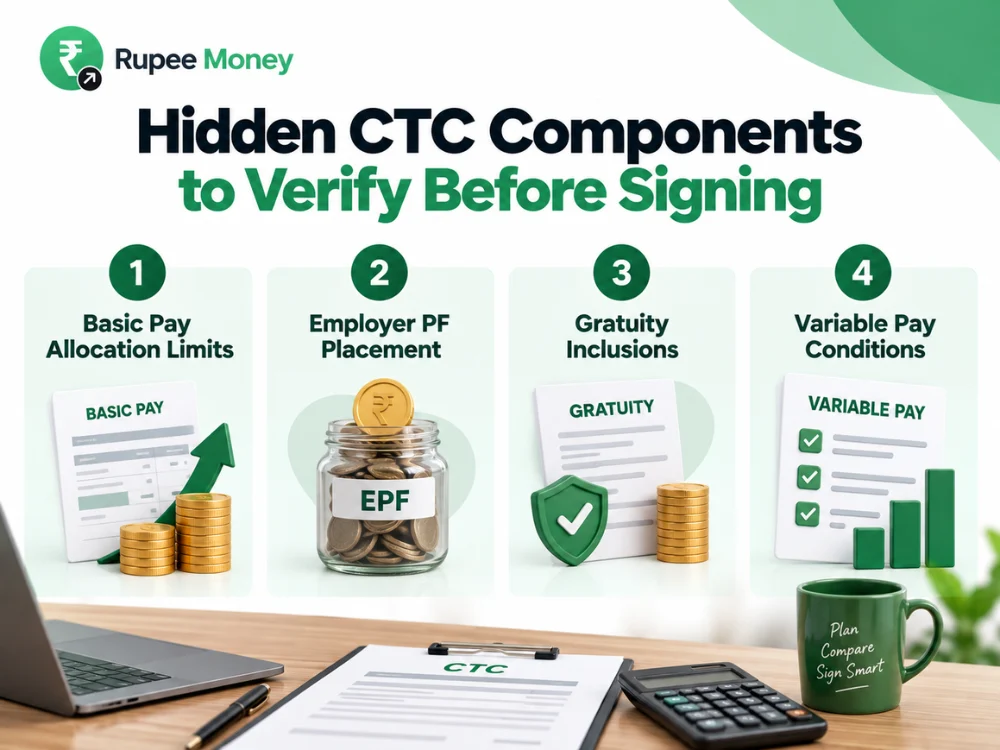
Reviewing the official offer letter meticulously prevents you from accepting an artificially inflated CTC that offers poor cash liquidity. You must verify several specific clauses before executing the employment contract.
Basic Pay Allocation Limits
A higher basic pay directly increases your mandatory EPF deductions. While this yields a slightly lower monthly in-hand salary, it rapidly builds a much stronger, tax-free retirement corpus over the long term. Conversely, a very low basic pay increases your immediate cash but stunts your retirement growth.
Employer PF Placement
Check diligently if the company embeds the employer’s 12% PF contribution inside the overall CTC figure. Doing so legally reduces your gross monthly cash. Highly transparent organizations often pay their employer PF share over and above the advertised CTC limit.
Gratuity Inclusions
Employers frequently highlight gratuity inside the CTC to inflate the overall headline number. Indian labor laws dictate that you only receive gratuity money after completing five continuous years of service with the exact same employer. Therefore, including it in your CTC makes it completely useless for your current monthly living expenses.
Variable Pay Conditions
Companies sometimes attach quarterly performance bonuses, attendance allowances, or annual incentives to the 3 LPA package. Treat variable pay strictly as a potential future bonus. Never calculate your monthly rent or essential living expenses relying on variable pay, as companies routinely withhold these payouts during poor business quarters or if you miss stringent performance targets.
Evaluating a 3 LPA Package for Freshers
Many recent graduates wonder if a ₹3,00,000 annual package provides a solid foundation for a long-term corporate career. The ultimate answer depends heavily on the specific industry sector, your current technical skill level, and your geographic location.
Earning this amount provides a highly comfortable starting point in tier-2 cities like Ahmedabad, Indore, or Jaipur. However, it requires strict financial discipline and careful budgeting in expensive metropolitan hubs like Mumbai, Delhi, or Bengaluru.
Look far beyond the immediate cash liquidity. Evaluate the entry-level role based on steep learning curves, direct executive mentorship availability, and the corporate brand value the organization adds to your resume. Acquiring high-income skills during your first two years sets the perfect stage for exponential, double-digit salary jumps later in your career.
Smart Budgeting Strategies for a ₹23,500 Income
Managing an entry-level take-home salary demands proactive, ruthless financial discipline. Allocating your funds using a strict mathematical framework ensures you cover daily necessities while simultaneously building a robust emergency fund. For a deeper dive into optimizing your early-career finances, explore comprehensive financial planning strategies.
- Housing and Core Utilities (₹7,000): Share an apartment with reliable roommates or stay in a registered PG accommodation to keep fixed rental overheads manageable.
- Groceries and Sustenance (₹4,000): Cook healthy, nutritious meals at home and pack your office lunches to entirely avoid expensive daily restaurant bills.
- Transportation and Commute (₹2,000): Utilize public transit networks, metro systems, or office carpools to commute efficiently and economically.
- Savings and Emergency Fund (₹4,000): Route this exact amount into a high-yield savings account or recurring deposit immediately on payday before you spend a single rupee.
- Personal Expenses and Leisure (₹2,500): Fund your entertainment, streaming subscriptions, and occasional weekend outings.
- Miscellaneous Buffer (₹4,000): Maintain a liquid cash buffer for unexpected medical pharmacy costs, mobile recharges, or immediate household repair needs.
Proven Strategies to Accelerate Salary Growth
You hold total control over your long-term career trajectory. A 3 LPA starting package simply acts as a professional launchpad; it does not dictate your permanent market value. You can rapidly increase your earning potential by mastering advanced technical tools highly relevant to your specific sector.
Secure industry-recognized certifications in high-demand fields like data analytics, digital marketing, enterprise sales, or cloud computing architecture. Build a verifiable digital portfolio showcasing successful corporate projects and quantifiable business results. When you consistently demonstrate direct, measurable value creation to executive leadership, negotiating a substantial raise or executing a strategic job switch becomes a seamless, highly rewarding process.
Conclusion
Securing a ₹3 LPA CTC represents a major, commendable milestone in your professional journey. While realizing that your monthly bank credit falls slightly short of the ₹25,000 mark can feel initially disappointing, you must remember that statutory deductions actively build your long-term retirement wealth through the secure EPF system. By aggressively controlling your living expenses, maximizing the massive tax exemptions available in the FY 2026-27 regime, and relentlessly investing in your own skill development, you transform this entry-level salary into a powerful stepping stone toward total financial independence. Always scrutinize your offer letter thoroughly, plan your budget proactively, and focus entirely on expanding your professional capabilities.
FAQs
What is the exact 3 LPA in hand salary per month?
The exact take-home amount depends heavily on your employer's specific payroll architecture. For most standard corporate packages, a 3 LPA monthly salary credits roughly ₹22,000 to ₹23,500 directly to your bank account after the payroll team deducts your mandatory Employee Provident Fund (EPF) and state professional taxes.
Does earning a 3 lakh package require income tax payments?
No, you do not pay income tax on this salary. Under the current new tax regime for the financial year 2026-27, the government completely exempts total annual income up to ₹4 lakh from all tax liabilities. You pay absolute zero income tax on a standard 3 LPA salary, ensuring you retain maximum cash liquidity.
Is ₹25,000 the guaranteed monthly bank credit?
No, ₹25,000 is not your final cash credit. While dividing ₹3,00,000 by 12 months equals ₹25,000, this mathematical figure represents your gross monthly equivalent. Statutory deductions like EPF and professional tax reduce this gross figure before the company transfers the final liquid cash to your account.
Does the CTC figure include employer PF contributions?
Yes, many companies strategically include the employer's 12% PF contribution inside the total Cost to Company (CTC) figure. When an employer structures the package this way, it further reduces the gross cash available for your monthly payout. Always demand a detailed, written salary breakup before officially signing the employment contract.
Is 3 LPA considered a respectable starting salary for freshers?
Industry experts generally consider a 3 LPA salary a strong, foundational starting point for freshers entering IT, operations, BPO, or digital marketing roles. It provides adequate financial stability to cover basic urban living expenses while you focus your energy entirely on acquiring advanced, high-income corporate skills.
The exact take-home amount depends heavily on your employer’s specific payroll architecture. For most standard corporate packages, a 3 LPA monthly salary credits roughly ₹22,000 to ₹23,500 directly to your bank account after the payroll team deducts your mandatory Employee Provident Fund (EPF) and state professional taxes.
Yes, many companies strategically include the employer’s 12% PF contribution inside the total Cost to Company (CTC) figure. When an employer structures the package this way, it further reduces the gross cash available for your monthly payout. Always demand a detailed, written salary breakup before officially signing the employment contract.
Disclaimer: This article serves general educational and informational purposes only. Specific payroll structures, EPF deductions, state-level professional taxes, and income tax treatments vary significantly based on individual employers, exact geographic locations, and rapidly evolving government legislation. The salary breakdowns and budgeting frameworks provided serve strictly as illustrative examples and do not constitute personalized tax, legal, or financial advice. Always scrutinize your official employment offer letter, verify internal corporate policies, and consult a certified financial planner or tax professional before making significant career or financial decisions.
ABOUT THE AUTHOR

