
RSU Taxation in India: How Are RSUs Taxed
Restricted Stock Units (RSUs) form a major part of modern employee compensation. Global technology firms and multinational corporations (MNCs) frequently use RSUs to reward their top talent. Instead of giving you an all-cash bonus, your employer grants you company shares that vest over a specified period. Welcome to RupeeMoney, your trusted guide for personal finance, tax compliance, and wealth creation.
While receiving company stock feels exciting, navigating RSU taxation can quickly become overwhelming. RSUs do not qualify as simple tax-free gifts. In fact, Indian tax laws treat RSUs under a distinct two-stage tax mechanism. You trigger tax liability first when your shares vest as salary income, and second when you eventually sell those shares as capital gains.
Failing to plan for this dual tax event can lead to severe cash-flow crunches, unexpected tax notices, and hefty compliance penalties. In this comprehensive guide, we break down RSU taxation India, explain how to calculate your tax liability, explore the tax rules for foreign tech stocks, and help you manage your equity compensation smartly.
What Are RSUs and How Do They Work?
A Restricted Stock Unit (RSU) is an employer’s contractual commitment to grant you company shares once you fulfill specific conditions. These conditions usually require you to stay with the company for a set duration or hit defined performance milestones.
Unlike traditional stock options, an RSU does not require you to pay an exercise price to purchase the shares. Once you meet the vesting conditions, the company delivers the shares directly to your brokerage account.
[Grant Date] ──> [Vesting Period / Milestones] ──> [Vesting & Share Delivery] ──> [Share Sale]
What Is the Difference Between Grant, Vesting, and Sale?
Understanding the RSU lifecycle requires tracking three distinct milestones:
- Grant Date: Your employer formally awards you a set number of RSUs. You do not own the actual shares yet, and you trigger zero tax liability on this date.
- Vesting Date: You satisfy the required time or performance criteria. The employer settles the RSUs and credits real company shares to your account. This milestone triggers your first major tax liability.
- Sale Date: You sell your vested shares in the open stock market. The difference between your sale price and the vesting price creates a capital gain or loss.
Why Do Multinational Companies Offer RSUs?
Companies use equity compensation to retain top talent and align employee incentives with long-term shareholder value. When the company performs well and its stock price rises, employees build substantial wealth. For young professionals, managing this equity forms a critical part of building wealth in your 20s.
What Is the Dual-Stage Framework of RSU Taxation India?
The Income Tax Act divides the taxation of RSU in India into two separate taxable events. You must evaluate each stage independently.
THE DUAL-STAGE RSU TAX FRAMEWORK
STAGE 1: At Vesting (Perquisite) Taxed under “Income from Salaries” Applies at your applicable slab rate
STAGE 2: At Sale (Capital Gains) Taxed under “Capital Gains” Rates depend on asset type & holding time
How Does Stage 1 Perquisite Tax on RSUs Work?
When your RSUs vest, the Indian tax department treats the entire market value of those shares as a non-monetary salary benefit (perquisite).
Your employer calculates the Fair Market Value (FMV) of the shares on the vesting date. The total perquisite value equals:
Perquisite Value = Number of Vested Shares ✕ FMV on Vesting Date – Amount Paid by Employee
Because you pay ₹0 to acquire standard RSUs, the entire market value becomes taxable salary income. Your employer adds this perquisite value to your monthly payslip and deducts Tax Deducted at Source (TDS) under Section 192 at your regular income tax slab rate (which often reaches 30% plus surcharge and cess for senior professionals).
How Does Stage 2 Capital Gains Tax Work?
When you decide to sell your vested shares, you trigger your second tax event. You calculate your capital gain by subtracting your cost basis from the final sale value:
Capital Gain = Sale Price – Cost of Acquisition (FMV on Vesting Date) – Transfer Expenses
The Indian tax code establishes the FMV on the vesting date as your official Cost of Acquisition. This vital rule prevents double taxation. You only pay capital gains tax on the additional profit generated after the vesting date.
How Is RSU Income Tax Calculated at Vesting?
To understand how RSU income tax works in practice, let us walk through a clear numerical example.
Imagine you work for an Indian subsidiary of a listed company. You receive a grant of 200 RSUs, and 50 shares vest this year.
- Number of Vested Shares: 50
- Fair Market Value on Vesting Date: ₹3,000 per share
- Total Taxable Perquisite Value: $50 \times ₹3,000 = ₹1,50,000$
Your employer adds this ₹1,50,000 directly to your gross salary. If your income falls in the 30% tax bracket (plus 4% cess, creating an effective rate of 31.2%), you face a tax liability of:
Stage 1 Tax = ₹1,50,000 ✕ 31.2\% = ₹46,800
| Transaction Step | Financial Value | Tax Treatment |
| 50 Shares Vest | ₹1,50,000 total FMV | Added to Gross Salary as a Perquisite |
| TDS Deducted | ₹46,800 | Employer withholds tax via salary or shares |
| Cost Basis Set | ₹3,000 per share | Becomes official cost basis for future capital gains |
What Is the RSU Tax Cash-Flow Problem?
RSUs present a unique cash-flow challenge. You receive non-cash company shares, but the government demands cash for taxes immediately.
If your employer does not withhold shares automatically, you must fund that ₹46,800 tax bill out of your normal monthly take-home salary. If multiple RSU tranches vest in a single month, your monthly cash paycheck can shrink to almost zero.
How Do Employers Manage TDS on RSUs?
Companies typically implement one of three operational methods to handle tax on RSUs at vesting:
- Sell-to-Cover: The international brokerage automatically sells just enough vested shares in the open market to cover your exact tax bill. They deposit the remaining shares in your account and remit the tax cash to your employer.
- Net Settlement (Withholding Shares): The company withholds a percentage of your vested shares equivalent to your tax liability. They issue you net shares and pay the cash tax directly to the tax department.
- Cash Funding: You transfer cash directly to your employer from your bank account to pay the required TDS, allowing you to retain 100% of your vested shares.
How Are Indian Listed RSUs Taxed on Sale?
If you receive shares of a company listed on the National Stock Exchange (NSE) or Bombay Stock Exchange (BSE), standard Indian capital gains rules apply:
- Short-Term Capital Gains (STCG): If you hold the shares for 12 months or less from the vesting date, your profits face a flat 20% tax under Section 111A.
- Long-Term Capital Gains (LTCG): If you hold the shares for more than 12 months, your profits face a 12.5% tax under Section 112A for aggregate long-term gains exceeding ₹1.25 lakh in a financial year.
How Does Foreign RSU Taxation Work for US Tech Stocks?
Most tech employees in Bengaluru, Hyderabad, and Pune receive RSUs from US-based parent companies like Google, Microsoft, Meta, or Amazon. Indian tax authorities treat foreign shares identically to domestic unlisted shares.
- Holding Period Threshold: The qualifying period for long-term status on foreign shares is 24 months from the vesting date.
- Short-Term Capital Gains (STCG): If you sell within 24 months, the entire profit is added to your total income and taxed at your regular income tax slab rate.
- Long-Term Capital Gains (LTCG): If you hold the foreign shares for more than 24 months, your profits face a flat 12.5% tax without indexation benefits.
Currency Conversion Formula (Rule 115)
When calculating capital gains on foreign shares, you must convert US Dollars to Indian Rupees using the State Bank of India (SBI) Telegraphic Transfer Buying Rate (TTBR) specified under Rule 115 of the Income Tax Rules.
Gain in INR = Sale Price in USD ✕ Sale Date TTBR – Vesting FMV in USD ✕ Vesting Date TTBR
Where Do Foreign Asset Reporting Rules (Schedule FA) Apply?
If you hold foreign RSUs, filing your Income Tax Return (ITR) requires strict diligence. Indian residents holding foreign company shares must comply with mandatory disclosure rules:
- Mandatory ITR Form: You cannot file ITR-1 (Sahaj) or ITR-4 (Sugam). You must file either ITR-2 or ITR-3.
- Schedule FA (Foreign Assets): You must declare every foreign brokerage account, the peak value of the holding during the year, total gross dividends received, and closing balances in Schedule FA.
- Schedule FSI and Schedule TR: If you pay withholding tax in the US on dividends (typically 25% under the US-India Double Taxation Avoidance Agreement), you report that income in Schedule FSI and claim Foreign Tax Credit (FTC) in Schedule TR by filing Form 67.
- Penalties for Non-Disclosure: The Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act imposes a severe flat penalty of ₹10 lakh for failing to disclose foreign assets in Schedule FA, even if you paid all your taxes on time.
How Do RSUs Differ From ESOPs and Sweat Equity?
While companies use both RSUs and ESOPs to reward employees, their operational structures differ significantly.
| Feature | Restricted Stock Units (RSUs) | Employee Stock Option Plans (ESOPs) |
| Basic Structure | A direct grant of full-value shares | An option to purchase shares at a fixed price |
| Exercise Price | Usually ₹0 (Zero purchase cost) | Pre-set exercise price (often discounted) |
| Primary Tax Trigger | On the day shares vest | On the day the option is exercised |
| Risk of Worthlessness | Shares always retain some market value | Options become worthless if share price falls below exercise price |
| Suitability | Established public MNCs and mature tech firms | Early-stage startups preparing for a future IPO |
What Happens to Your RSUs When You Leave Your Job?
Changing jobs directly alters your equity compensation portfolio:
- Vested Shares: All shares that have already vested remain your permanent property. You can keep holding them in your overseas brokerage account or sell them whenever you choose.
- Unvested Shares: When you resign or face termination, you forfeit all unvested RSUs immediately. The company cancels these units and returns them to the corporate equity pool.
- Retirement or Layoffs: Many corporate equity plans include acceleration clauses that automatically vest a portion of your unvested RSUs in the event of redundancy or standard retirement.
Why Is Capital Loss Planning Vital If Share Prices Drop?
Stock markets experience sharp swings, and heavy tech volatility can push share prices down.
Imagine your RSUs vest at an FMV of $150. You pay salary tax on that $150 valuation. Six months later, tech stocks tumble, and you sell the shares at $100.
You incur a Capital Loss of $50 per share. You cannot retroactively reclaim the salary perquisite tax you already paid on the $150 valuation. However, under Indian tax laws, you can set off this short-term capital loss against other taxable capital gains (like gains from mutual funds or property) and carry forward unadjusted losses for up to 8 consecutive financial years.
What Common Mistakes Should Employees Avoid in RSU Taxation?
Employees frequently make costly errors when managing their equity compensation:
- Treating RSUs as Free, Tax-Free Shares: Every vested unit adds to your taxable salary.
- Ignoring Schedule FA Disclosures: Forgetting to declare foreign brokerage accounts in your ITR invites scrutiny under the Black Money Act.
- Double Taxation Errors: Using a ₹0 cost basis instead of the vesting FMV when calculating capital gains forces you to pay tax on the same income twice.
- Failing to File Form 67: If your US broker withholds tax on your dividends, you must submit Form 67 before filing your ITR to claim credit under the DTAA.
- Over-Concentrating in Employer Stock: Holding 80% of your total net worth in your employer’s stock exposes you to severe risk. Practice disciplined portfolio diversification by periodically selling vested shares and reallocating to index funds tracking the Nifty 50.
How Can You Build a Smart Financial Strategy Around RSUs?
To maximize the real-world value of your equity awards, integrate your RSU vesting schedule into your overall financial planning:
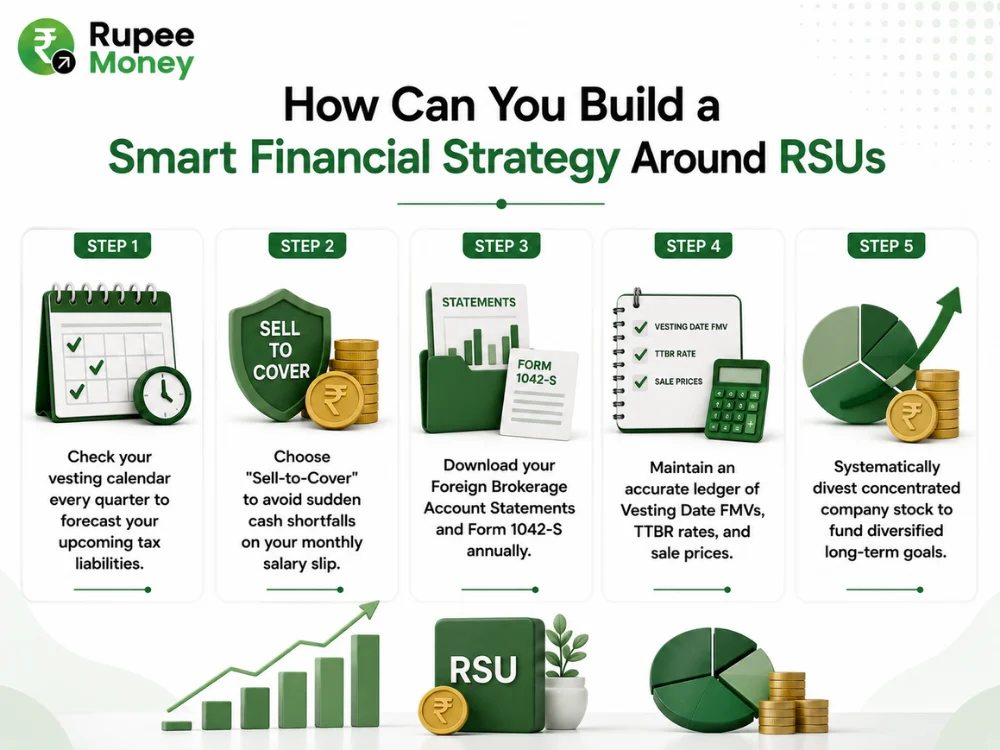
Step 1: Check your vesting calendar every quarter to forecast your upcoming tax liabilities.
Step 2: Choose “Sell-to-Cover” to avoid sudden cash shortfalls on your monthly salary slip.
Step 3: Download your Foreign Brokerage Account Statements and Form 1042-S annually.
Step 4: Maintain an accurate ledger of Vesting Date FMVs, TTBR rates, and sale prices.
Step 5: Systematically divest concentrated company stock to fund diversified long-term goals.
Conclusion
Restricted Stock Units represent a transformative wealth-building vehicle for corporate professionals. However, maximizing their true value requires mastering RSU taxation India.
Always separate your compensation tax at vesting from your capital gains tax at sale. Keep meticulous records of your grant letters, vesting statements, Fair Market Values, and State Bank of India exchange rates. Ensure complete compliance by reporting foreign assets accurately in Schedule FA and claiming foreign tax credits via Form 67.
By taking a proactive approach to tax on RSUs, managing your cash flows, and periodically reallocating into a diversified investment portfolio, you can turn your company equity into lifelong financial independence. Explore more actionable personal finance guides on RupeeMoney to take full control of your wealth today.
FAQs
What is RSU taxation in India?
RSU taxation in India is a two-stage tax process. The market value of shares on the vesting date is taxed as salary income (perquisite). Any subsequent increase in share price is taxed as capital gains when you sell the shares.
Are RSUs taxed twice in India?
No, RSUs are not double-taxed on the same income. You pay income tax on the market value at vesting. When you sell, that same vesting value becomes your cost basis, ensuring you only pay capital gains tax on the additional profit generated after vesting.
What is the tax rate on foreign RSUs in India?
At vesting, foreign RSUs are taxed at your regular income tax slab rate. When sold, short-term capital gains (held $le$ 24 months) are taxed at your income slab rate, while long-term capital gains (held $>$ 24 months) face a flat 12.5% tax rate without indexation.
Which ITR form should I file if I have foreign RSUs?
You must file ITR-2 (for salaried individuals) or ITR-3 (for individuals with business/profession income). You cannot file ITR-1 if you hold foreign equity or foreign bank/brokerage accounts.
What happens if I do not report my foreign RSUs in Schedule FA?
Failing to declare foreign shares and overseas brokerage accounts in Schedule FA of your ITR can attract a flat penalty of ₹10 lakh under the Black Money Act, along with potential tax scrutiny.
At vesting, foreign RSUs are taxed at your regular income tax slab rate. When sold, short-term capital gains (held $\le$ 24 months) are taxed at your income slab rate, while long-term capital gains (held $>$ 24 months) face a flat 12.5% tax rate without indexation.
Disclaimer: This article is published solely for educational and informational purposes and does not constitute formal tax, legal, or financial advice. Indian tax laws, international DTAA rules, and capital gains frameworks change frequently. Always consult a certified Chartered Accountant or qualified tax advisor to evaluate your specific tax filing requirements.
ABOUT THE AUTHOR

