
SWP Mutual Funds: How Systematic Withdrawals Work
Investors often build a massive retirement corpus but struggle to convert it into a regular income stream. An SWP mutual fund solves this exact problem.
A Mutual Fund SWP allows you to withdraw a fixed amount of money from your investments at regular intervals. SWP stands for Systematic Withdrawal Plan. It helps investors create a steady cash flow while keeping the rest of their money actively invested in the market. Welcome to RupeeMoney, your trusted financial guide. Let us explore exactly how this powerful cash flow tool works.
Unlike liquidating your entire portfolio at once, an SWP mutual fund strategy redeems a predetermined number of units periodically. You can choose to withdraw money monthly, quarterly, or half-yearly. This makes it an ideal mutual fund withdrawal plan for retirees or those needing supplementary income.
However, you must respect the risks. An SWP does not guarantee fixed returns. It does not protect your capital from market crashes. This guide explains what a Mutual Fund SWP is, how it functions, and how to use an SWP calculator to plan your financial future securely.
What Is a Mutual Fund SWP?
Mutual Fund SWP is a facility provided by asset management companies. It allows you to withdraw a specific amount from your existing mutual fund investment at regular intervals.
Imagine you accumulate ₹10 lakh in a mutual fund. You register an SWP for ₹20,000 per month. The fund house will automatically redeem enough units every month to pay you ₹20,000. They transfer this money directly to your registered bank account. The remaining units in your portfolio continue to stay invested and grow.
How Does an SWP Mutual Fund Work?
Setting up an SWP mutual fund involves a very simple process.
- You invest money into an eligible mutual fund scheme.
- You accumulate units over several years.
- You register an SWP instruction with the fund house.
- You select the exact withdrawal amount and frequency.
- The fund house redeems units equivalent to your required amount.
- The fund house credits the money to your bank account.
The most important detail is the unit redemption. The number of units redeemed changes every month because the mutual fund’s Net Asset Value (NAV) fluctuates daily.
How Does SWP Mutual Fund Withdrawal Work?
Many beginners mistakenly believe an SWP pays out interest or dividends. That is incorrect. The mutual fund specifically redeems (sells) units from your holdings.
Suppose you own 1,000 units of a fund. The current NAV is ₹100. Your total investment value is ₹1,00,000.
If you set an SWP to withdraw ₹10,000, the fund house must sell 100 units (100 units × ₹100 NAV = ₹10,000). You will then have 900 units remaining in your account.
Why Does the Number of Units Matter?
Because an SWP forces unit redemption, the current NAV dictates your portfolio’s health.
- When the market is high and the NAV rises, the fund house sells fewer units to meet your withdrawal amount.
- When the market crashes and the NAV drops, the fund house must sell more units to meet the same withdrawal amount.
Selling too many units during a market crash can destroy your long-term wealth. This makes planning your withdrawal rate incredibly important.
What Is an SWP Calculator?
An SWP calculator is a digital financial planning tool. It estimates how your investment corpus will behave when you start making regular withdrawals.
When you use the calculator, you enter specific details:
- Initial investment corpus.
- Expected annual return rate.
- Monthly withdrawal amount.
- Investment duration.
The calculator processes these numbers instantly. It estimates your total withdrawals, your final remaining corpus, and how long your money will realistically last.
How Does an SWP Calculator Work?
An SWP calculator uses complex compound interest math. It assumes a fixed rate of return and calculates the portfolio balance after every monthly withdrawal.
For example, imagine you invest ₹20 lakh. You withdraw ₹25,000 monthly. If you assume an 8% annual return, the calculator will project your portfolio balance for the next ten years. You can easily test these numbers using RupeeMoney’s official SWP Calculator.
Remember, this is a mathematical projection. Actual mutual fund returns fluctuate wildly based on market conditions.
How Is SWP Different From SIP?
Many investors confuse these two terms. SIP and SWP represent exact opposite directions of cash flow.
What Is SIP?
A Systematic Investment Plan (SIP) allows you to invest a fixed amount of money into a mutual fund every month. Money moves from your bank account into the mutual fund. You use it to build wealth.
What Is SWP?
A Systematic Withdrawal Plan allows you to pull a fixed amount of money out of an existing mutual fund every month. Money moves from the mutual fund into your bank account. You use it to consume wealth.
Smart investors combine both tools. They use SIPs during their working years to accumulate wealth. They use SWPs during retirement to generate regular income.
Why Do Investors Use a Mutual Fund Withdrawal Plan?
A mutual fund withdrawal plan helps investors structure their cash flow intelligently. Random lump-sum withdrawals can trigger heavy taxes and deplete portfolios too quickly.
Investors primarily use SWPs for:
- Creating a monthly “salary” during retirement.
- Paying regular EMIs or household expenses.
- Supplementing a lower monthly income.
- Meeting planned financial commitments systematically.
How Can SWP Support Retirement Planning?
Retirees often sit on a massive corpus but lack a monthly paycheck. An SWP solves this perfectly. It provides a structured paycheck while keeping the bulk of the retirement corpus actively invested in the market to beat inflation.
However, retirees must plan the withdrawal amount carefully. Extracting too much money too fast will destroy the corpus entirely.
What Is the Best SWP Mutual Fund?
Investors constantly search for the best SWP mutual fund. The truth is, no single fund fits every investor perfectly.
The right scheme depends heavily on your specific needs:
- Your total investment horizon.
- Your personal risk tolerance.
- Your required monthly withdrawal amount.
- Your overall asset allocation strategy.
Never select a fund just because it posted high historical returns last year.
How Should You Evaluate the Best SWP Mutual Fund?
When choosing an SWP fund, prioritize stability over aggressive growth. Look for low volatility, consistent returns, and high-quality portfolio assets.
If you need stable withdrawals over the next three years, a highly volatile small cap mutual fund is a terrible choice. A conservative hybrid fund or an equity savings fund provides much safer grounds for regular withdrawals.
How Much Should You Withdraw Through SWP?
Your withdrawal amount must align proportionally with the total size of your corpus.
Withdrawing ₹50,000 monthly from a ₹50 lakh corpus represents a massive 12% annual withdrawal rate. This will deplete your funds rapidly. Withdrawing the same ₹50,000 from a ₹2 crore corpus represents a safe 3% withdrawal rate.
Why Is Withdrawal Rate Important?
A high withdrawal rate destroys your investment corpus permanently. This becomes extremely dangerous during bear markets. If the market drops 20% and you continue withdrawing 10% annually, your portfolio will bleed out. You must ensure your withdrawal rate remains lower than your expected annual return.
What Is the Risk of SWP Mutual Fund Investments?
An SWP mutual fund is not a guaranteed income product. You remain completely exposed to market risks.
What Happens If the Market Falls?
If the mutual fund’s NAV crashes, the fund house must redeem significantly more units to generate your fixed monthly payout. This permanently reduces the number of units you own. When the market eventually recovers, you will have fewer units left to participate in the rally.
What Is Sequence of Returns Risk?
This is the deadliest risk for SWP investors. Imagine two retirees with the exact same corpus and the same withdrawal rate.
- Retiree A faces a brutal market crash in the first two years of retirement.
- Retiree B enjoys a massive bull run in the first two years.
Retiree A must sell a massive number of units at deeply discounted prices just to survive. Their portfolio might never recover. Retiree B sells very few units at premium prices, preserving their wealth easily. The timing of market crashes deeply impacts SWP success.
How Does Inflation Affect a Mutual Fund Withdrawal Plan?
Inflation constantly erodes your purchasing power. A fixed SWP payout loses value over time.
Suppose you start an SWP of ₹30,000 per month today. Ten years from now, that ₹30,000 will buy significantly fewer groceries. Therefore, long-term withdrawal planning must account for rising expenses.
Can SWP Be Increased Over Time?
Yes. Many modern fund houses offer “Top-up SWP” facilities. This feature allows you to increase your withdrawal amount by a specific percentage (like 5%) every year to combat inflation directly.
How Is SWP Taxed?
Taxation makes the SWP mutual fund incredibly attractive. When you withdraw money via SWP, the government does not tax the entire withdrawal amount.
The tax department treats SWP withdrawals as capital gains, not as ordinary income. The tax only applies to the specific profit generated on the redeemed units.
What Determines the Tax?
The exact tax you pay depends on:
- The type of mutual fund (Equity or Debt).
- Your specific holding period (Short-term or Long-term).
- The applicable capital gains tax rules for that financial year.
For equity funds, long-term capital gains over ₹1.25 lakh face a 12.5% tax rate. Short-term gains face a 20% flat tax rate.
What Is the Difference Between SWP and Dividend Income?
Many older investors prefer dividend payout options. However, SWP and dividends work very differently.
A dividend payout depends entirely on the fund house. They decide when to pay it and how much to pay. You have zero control.
An SWP puts you in total control. You decide exactly how much money you need and exactly when you want it. For investors seeking predictable monthly cash flow, the SWP always wins.
When Should You Start an SWP?
No universal age rule dictates when you must start an SWP. It depends entirely on your financial milestones.
You might start an SWP:
- Immediately after retiring from your job.
- After building a massive corpus and deciding to take a career break.
- When you need to pay a regular EMI and want your investments to cover it.
How Can You Plan an SWP Effectively?
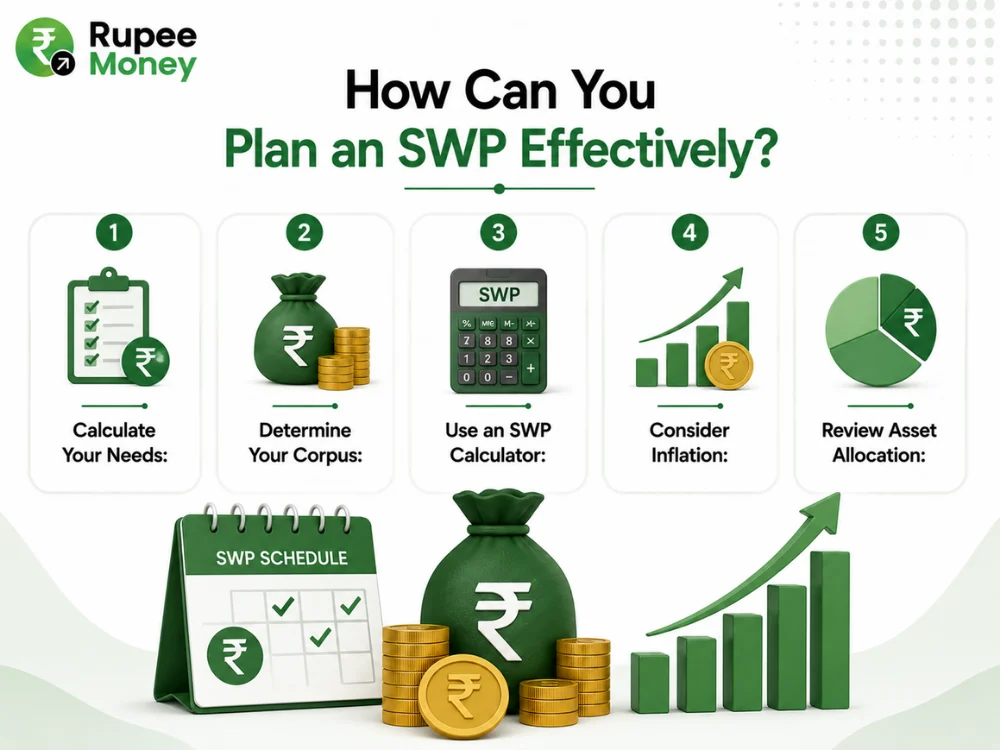
Follow a strict planning process to avoid draining your wealth prematurely.
- Calculate Your Needs: Define your exact monthly expense requirement.
- Determine Your Corpus: Know exactly how much capital you hold.
- Use an SWP Calculator: Test various withdrawal rates on the SWP calculator to ensure sustainability.
- Consider Inflation: Factor in rising living costs over the next decade.
- Review Asset Allocation: Ensure your portfolio is not 100% exposed to high-risk equities.
What Are the Advantages of Mutual Fund SWP?
- Regular Cash Flow: Provides a reliable, automated monthly paycheck.
- Total Flexibility: You can stop, start, or modify the withdrawal amount anytime.
- Continued Growth: Your unredeemed units remain invested and compound over time.
- Tax Efficiency: Capital gains taxation is far cheaper than ordinary income tax slabs.
What Are the Disadvantages of SWP Mutual Funds?
- Market Risk: A sudden market crash can heavily deplete your unit balance.
- Corpus Depletion: Withdrawing too aggressively will bankrupt your portfolio.
- Inflation Risk: A static payout loses purchasing power over decades.
Where Does SWP Fit Into a Financial Plan?
An SWP serves strictly as a cash flow distribution mechanism. It is the final phase of a complete financial planning lifecycle.
The lifecycle flows sequentially:
Accumulation (via SIP) → Corpus Creation → Asset Allocation → Systematic Withdrawals (via SWP).
You must structure your underlying portfolio according to your actual risk capacity before activating the SWP.
Conclusion: How Does SWP Mutual Fund Withdrawal Work?
A Mutual Fund SWP provides the most structured, tax-efficient way to generate a regular income from your accumulated investments. Instead of withdrawing your entire corpus at once, you redeem small portions periodically while the rest of your money continues compounding in the market.
Using an SWP calculator helps you project exactly how different withdrawal rates impact your portfolio’s longevity. However, always remember these projections are not guarantees. Mutual funds remain market-linked.
Choosing the best SWP mutual fund requires careful thought. You must align the fund’s risk profile with your actual cash flow needs. Most importantly, remember that an SWP is not a magic infinite-money machine. If you withdraw too aggressively, or if the market suffers a prolonged crash, your corpus will deplete. Plan your withdrawal rate conservatively so that today’s income never compromises your financial security tomorrow.
FAQs
What is Mutual Fund SWP?
It is a facility that allows you to withdraw a fixed predetermined amount from your mutual fund investments at regular intervals.
How does an SWP mutual fund work?
The fund house automatically redeems a specific number of your units at the current NAV to generate your requested withdrawal amount.
What is an SWP calculator?
An SWP calculator is a digital tool that projects how your investment corpus will deplete or grow based on your withdrawal amount and assumed rate of return.
What is the best SWP mutual fund?
The best SWP mutual fund depends entirely on your specific risk profile. Conservative hybrid funds or balanced advantage funds often work best for stable SWP cash flows.
Is SWP better than withdrawing a lump sum?
Yes. SWP provides structured cash flow, keeps the remaining money invested for growth, and is far more tax-efficient than pulling out a massive lump sum.
Can SWP provide guaranteed income?
No. An SWP does not guarantee returns. Your portfolio remains fully exposed to market risks and NAV fluctuations.
Can I change my SWP amount?
Yes. You retain total control. You can increase, decrease, or completely cancel your SWP instructions anytime without penalties.
Is SWP taxable?
Yes, but highly efficiently. You only pay capital gains tax on the profit portion of the specific units redeemed that month.
Can SWP reduce my mutual fund balance?
Yes. If your monthly withdrawal amount exceeds the monthly growth generated by the market, your overall portfolio balance will decline.
Can I use SWP after SIP?
Absolutely. SIP is the tool you use to build the wealth. SWP is the tool you use to consume the wealth during retirement.
An SWP calculator is a digital tool that projects how your investment corpus will deplete or grow based on your withdrawal amount and assumed rate of return.
The best SWP mutual fund depends entirely on your specific risk profile. Conservative hybrid funds or balanced advantage funds often work best for stable SWP cash flows.
Disclaimer: This article is strictly for educational and informational purposes and does not constitute financial, investment, or tax advice. Mutual fund investments are subject to market risks. Past performance is not indicative of future results. Always consult a SEBI-registered financial advisor before starting any systematic withdrawal plan.
ABOUT THE AUTHOR

