
Equity Savings Funds: How They Work, Risks and Tax Treatment
Every investor searches for the ideal balance between growth and safety. Pure equity funds offer strong growth, but they bring high market volatility. Debt funds offer stability, but recent tax rule changes have reduced their post-tax appeal. Welcome to RupeeMoney, your trusted destination for smart investing and wealth creation. If you want equity exposure with lower risk and favorable tax rules, an equity savings fund can serve as an ideal middle ground.
An equity savings mutual fund is a unique hybrid investment. It blends three distinct asset classes into a single scheme: directional equity, arbitrage strategies, and fixed-income debt securities. By doing so, it aims to capture equity market upside while cushioning your portfolio during sharp market downturns.
Under the guidelines of the Securities and Exchange Board of India (SEBI), every scheme in this category must allocate at least 65% of its total assets to equity and equity-related instruments. Additionally, the fund must invest a minimum of 10% in debt instruments. Because fund managers hedge a large part of the equity exposure using derivatives, the actual market risk remains far lower than what the headline numbers suggest.
Let us examine what are equity savings funds, how they generate returns, their core risks, and why their tax structure makes them popular among smart investors.
What Are Equity Savings Funds?
What are equity savings funds in simple terms? They are open-ended hybrid mutual funds that spread your money across three specific engines:
- Unhedged Equity: The fund manager buys shares directly to generate long-term capital growth.
- Arbitrage Positions: The manager exploits price differences between the cash and derivatives markets to earn low-risk returns.
- Debt Securities: The fund invests in bonds and money market instruments to earn steady interest income.
Instead of managing three separate portfolios on your own, an equity savings fund combines these assets under one roof. The fund manager rebalances the allocations actively based on market conditions. This structure delivers higher stability than pure equities and better post-tax returns than traditional fixed deposits.
What Makes an Equity Savings Mutual Fund Different?
A traditional equity scheme maintains an unhedged, directional exposure of 90% to 100% in stocks. When the broader market crashes, the Net Asset Value (NAV) of a pure equity fund plunges rapidly.
An equity savings mutual fund operates on a different philosophy. While its gross equity allocation stays at or above 65% to qualify for equity taxation, its net active equity exposure usually stays between 20% and 40%. The remaining equity portion remains fully hedged through derivative contracts.
Gross Equity (≥ 65%) = Net Unhedged Equity (20% – 40%) + Hedged Arbitrage (25% – 45%)
Remaining Assets (≥ 10%) = High-Quality Debt & Money Market Instruments
This dual structure shields your capital. When stock markets experience extreme stock volatility, the hedged arbitrage and debt components protect the overall portfolio value.
How Do Equity Savings Funds Work?
An equity savings fund relies on three distinct engines to build wealth. Each engine performs a dedicated role within the portfolio.
How Does the Equity Portion Work?
The equity component focuses on direct stock selection. The fund manager picks fundamentally strong companies across large-cap, mid-cap, and small-cap segments. When these companies grow their earnings, their share prices rise, driving the fund’s NAV upward. This active portion provides the growth power needed to beat inflation over the long run.
How Does the Arbitrage Portion Work?
Arbitrage generates risk-free or low-risk profits from simultaneous trades in different market segments. The fund manager identifies pricing mismatches between the spot cash market and the futures market.
For instance, if a stock trades at ₹1,000 in the cash market and ₹1,007 in the futures market, the manager buys the stock in cash and sells the futures contract simultaneously. At expiry, both prices converge, allowing the fund to lock in a ₹7 profit regardless of market direction.
How Does the Debt Portion Work?
The debt component holds fixed-income securities. These include Treasury Bills, Government Securities (G-Secs), Corporate Bonds, and Certificates of Deposit. This segment generates steady interest income and adds liquidity. It acts as a shock absorber when equity markets tumble.
Why Do Equity Savings Funds Use Arbitrage?
Arbitrage plays a clever dual role in an equity savings fund.
First, it creates low-risk returns. Because the manager buys and sells equal quantities simultaneously, market rallies or crashes do not impact this position. The trade locks in a fixed spread.
Second, SEBI rules treat hedged arbitrage positions as equity-related instruments. This legal definition allows the fund to maintain its mandatory 65% gross equity threshold without taking excessive directional market risk. You enjoy the low-risk profile of a debt-oriented structure while retaining the tax benefits of an equity fund.
Where Do Equity Savings Funds Fit in a Portfolio?
Asset allocation dictates your long-term investing success. An equity savings mutual fund fits perfectly into the conservative-to-moderate bucket of your overall financial planning.
- Medium-Term Goals: If you need funds in 2 to 4 years for a car purchase or home down payment, pure equities carry too much risk. An equity savings scheme offers better growth potential than bank FDs with controlled risk.
- First-Time Equity Investors: If you are transitioning from traditional fixed deposits to the stock market, jumping directly into pure equity can feel intimidating. This fund category cushions your entry.
- Retirees and Conservative Savers: Retirees who need regular cash flows can set up a Systematic Withdrawal Plan (SWP) from an equity savings fund. The lower volatility preserves the capital base.
What Are the Risks of Equity Savings Funds?
While an equity savings fund carries lower risk than pure equity products, it is not a zero-risk investment. Investors must understand the underlying risks before allocating money.
What Is the Equity Market Risk?
The unhedged equity component (20% to 40%) remains exposed to stock market declines. If broader equity markets undergo a major correction, this unhedged portion will lose value, pulling down the fund’s NAV.
What Is the Debt Risk?
The fixed-income portion faces two primary threats:
- Interest Rate Risk: When the Reserve Bank of India hikes repo rates, bond prices drop, impacting debt returns.
- Credit Risk: If a bond issuer defaults on interest or principal payments, the fund suffers a direct write-down.
What Is the Arbitrage Risk?
Arbitrage spreads fluctuate based on market sentiment. During volatile or sideways markets, spreads widen, generating healthy yields. In dull or highly pessimistic markets, arbitrage spreads compress, reducing the income generated by this portion.
Can Equity Savings Funds Lose Money?
Yes. An equity savings fund can deliver negative returns over short horizons. If the unhedged equity portion crashes while debt securities face credit downgrades, the overall NAV will drop. Never treat this fund as a guaranteed capital-protection product.
Why Is Tax Treatment Important for Equity Savings Funds?
Tax efficiency is the biggest selling point of an equity savings mutual fund. The Finance Act has eliminated indexation benefits for pure debt mutual funds, taxing debt fund gains at your slab rate.
Because an equity savings fund maintains at least 65% gross exposure in equity and arbitrage, tax authorities classify it as an equity-oriented mutual fund. This distinction delivers massive tax savings for investors in the 20% and 30% tax brackets.
How Long Must You Hold an Equity Savings Fund?
The holding period determines whether you pay short-term or long-term capital gains tax:
| Holding Period | Classification | Applicable Tax Rate |
| 12 Months or Less | Short-Term Capital Gains (STCG) | 20% flat (+ applicable surcharge & cess) |
| More than 12 Months | Long-Term Capital Gains (LTCG) | 12.5% on gains exceeding ₹1.25 lakh per financial year |
You pay zero tax on your first ₹1.25 lakh of cumulative long-term capital gains across all equity investments in a single financial year.
How Is Equity Savings Fund Tax Different From Debt Funds?
Consider an investor in the 30% tax bracket who earns ₹2,00,000 in capital gains after holding an investment for two years:
- In a Pure Debt Fund: The entire ₹2,00,000 is added to taxable income and taxed at 30% (plus cess), resulting in roughly ₹62,400 in taxes.
- In an Equity Savings Fund: The first ₹1,25,000 is tax-exempt under Section 112A. The remaining ₹75,000 is taxed at 12.5% (plus cess), resulting in roughly ₹9,750 in taxes.
This massive tax differential helps investors retain a significantly higher portion of their investment gains.
What Are the Advantages of Equity Savings Funds?
Investing in an equity savings fund provides several distinct benefits for modern portfolios.
Why Can They Offer Lower Volatility?
The three-way asset split prevents sharp portfolio swings. While the unhedged equity drives growth during bull runs, the steady debt income and market-neutral arbitrage buffer the portfolio during market corrections.
Why Can They Offer Equity Taxation?
By using derivative contracts to reach the mandatory 65% equity threshold, the fund qualifies legally for equity taxation rules. You enjoy favorable long-term capital gains rates without taking 100% directional equity risk.
Why Are They Diversified?
A single fund gives you exposure to top-tier equities, derivative arbitrage trades, corporate bonds, and government paper. This multi-layer portfolio diversification eliminates the hassle of tracking and rebalancing multiple individual assets.
Why Can They Be Useful for Moderate-Risk Investors?
Moderate-risk savers often struggle between low-yielding fixed deposits and high-risk equity schemes. This fund category provides an optimal bridge, targeting higher returns than fixed-income instruments while keeping drawdown risk within acceptable limits.
What Are the Disadvantages of Equity Savings Funds?
Despite their advantages, equity savings schemes carry limitations that every investor must evaluate.
What Is the Return Limitation?
Because only 20% to 40% of the portfolio sits in unhedged equities, this fund will significantly lag behind pure large-cap mutual funds during roaring bull markets. If the Nifty 50 surges 25%, an equity savings fund might only return 9% to 12%.
What Is the Complexity?
Understanding how fund managers execute arbitrage spreads, manage derivative roll-overs, and maintain credit quality requires financial literacy. Novice investors often mistake these funds for pure debt or pure equity products.
What Are the Costs?
Active management across equities, derivatives, and fixed-income paper involves higher portfolio turnover. Ensure you choose direct mutual funds vs regular mutual funds to eliminate distributor commissions and keep expense ratios low.
Why Is Tax Classification Important?
Fund managers must strictly maintain the 65% gross equity average throughout the year. If a scheme fails to meet this threshold due to sudden market shifts, it risks losing its equity tax status. Always pick established fund houses with proven track records.
When Should You Consider an Equity Savings Fund?
You should consider investing in an equity savings fund under the following financial circumstances:
- You have a medium-term investment horizon of 2 to 4 years.
- You want higher post-tax returns than traditional fixed deposits and recurring deposits.
- You want to start a Systematic Investment Plan (SIP) without experiencing heavy market volatility.
- You belong to the 20% or 30% income tax slab and want to legally minimize your capital gains tax.
- You plan to set up a monthly SWP to generate tax-efficient supplementary income during retirement.
How Should You Choose an Equity Savings Mutual Fund?
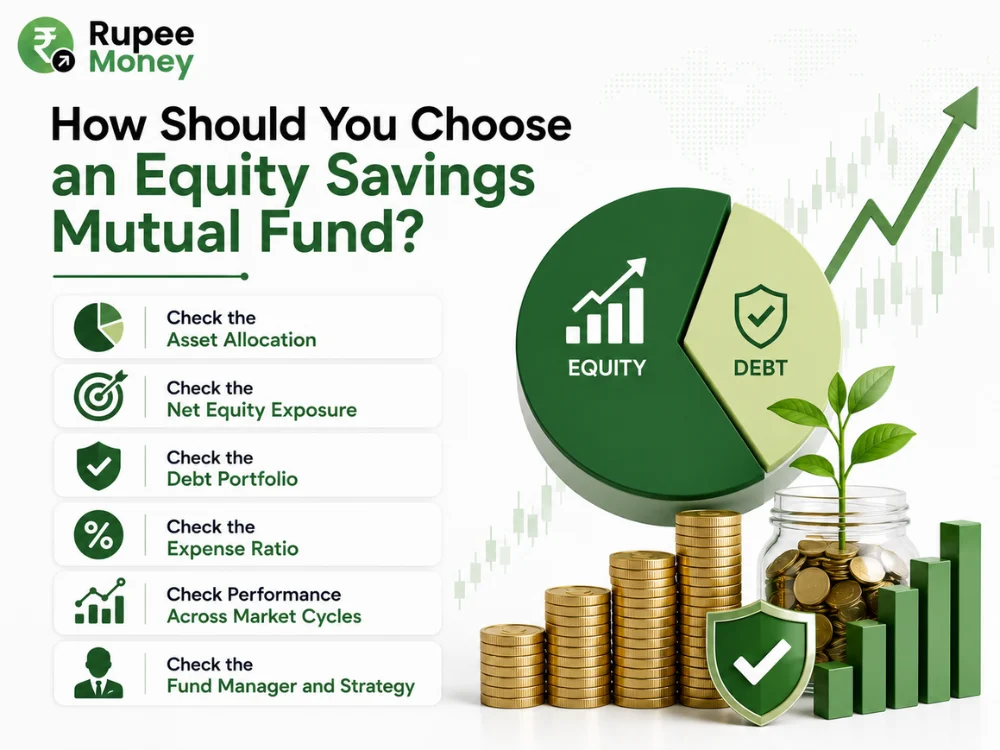
Not all schemes in this category follow the same strategy. Use this checklist to select the best fund for your portfolio:
Check the Asset Allocation
Review the latest factsheet. Examine the exact split between active equity, hedged arbitrage, and debt securities.
Check the Net Equity Exposure
Look at the net directional equity exposure. A fund with 40% net equity will behave aggressively, while a fund with 20% net equity will offer higher stability. Match this percentage to your personal risk tolerance.
Check the Debt Portfolio
Scrutinize the credit quality of the fixed-income allocation. Ensure the manager invests primarily in AAA-rated corporate papers, sovereign bonds, and high-quality money market instruments. Avoid schemes that take credit risks to boost yields.
Check the Expense Ratio
High expense ratios erode your compounding returns over time. Compare expense ratios across competing fund houses and choose direct plans.
Check Performance Across Market Cycles
Evaluate how the fund protected downside capital during previous market corrections. Consistent performance across both bull and bear markets matters more than a single year’s high return.
Check the Fund Manager and Strategy
Look at the experience of the fund management team. Managing simultaneous equity selection, derivative hedging, and bond duration requires strong execution capabilities.
How Are Equity Savings Funds Different From Other Mutual Funds?
To see where this category stands, compare it against other core mutual fund categories:
| Feature | Equity Savings Fund | Pure Equity Fund | Pure Debt Fund | Conservative Hybrid Fund |
| Gross Equity | Minimum 65% | 80% to 100% | 0% | 10% to 25% |
| Net Unhedged Equity | 20% to 40% | 80% to 100% | 0% | 10% to 25% |
| Arbitrage Engine | Yes (25% to 45%) | No | No | Rare |
| Debt Exposure | 10% to 35% | 0% to 10% | 90% to 100% | 75% to 90% |
| Volatility Level | Low to Moderate | High to Very High | Very Low | Low |
| Tax Status | Equity Tax (12.5% LTCG) | Equity Tax (12.5% LTCG) | Slab Rate (No Indexation) | Slab Rate (No Indexation) |
| Ideal Horizon | 2 to 4 Years | 5+ Years | 1 to 3 Years | 3 to 5 Years |
What Should Investors Remember About Equity Savings Funds?
Never buy an equity savings fund expecting quick riches. It is a conservative wealth-preservation and steady-growth tool.
Remember these core truths:
- It will not beat a pure equity fund during roaring bull markets.
- It will not guarantee fixed returns like a bank deposit.
- Its primary advantage is providing equity-like taxation with debt-like stability.
By setting realistic return expectations of 8% to 11% over 3-year cycles, you can use these funds to achieve your financial milestones with peace of mind.
Conclusion: Are Equity Savings Funds Right for You?
An equity savings fund solves a major dilemma for Indian investors. It eliminates the high volatility of direct stock investing while rescuing your returns from the punitive tax rules of pure debt instruments.
By combining active equities for growth, arbitrage for low-risk yield, and fixed-income bonds for steady stability, this category delivers a reliable, all-weather investment solution. If you want to grow your wealth steadily, beat inflation, and protect your hard-earned gains from excessive taxation, an equity savings mutual fund deserves a prominent place in your portfolio. Plan your contributions wisely through a disciplined SIP on RupeeMoney to secure your financial future today.
FAQs
What are equity savings funds?
They are hybrid mutual funds that invest in a combination of direct equity, derivative arbitrage strategies, and fixed-income debt instruments. SEBI mandates a minimum 65% gross allocation to equity-related instruments and at least 10% to debt.
What is an equity savings mutual fund?
An equity savings mutual fund is a professionally managed collective investment scheme that aims to provide capital appreciation and regular income while keeping downside volatility lower than pure stock funds.
Why do equity savings funds use arbitrage?
Arbitrage allows the fund manager to generate low-risk spreads while satisfying the 65% gross equity rule required for equity tax benefits.
Are equity savings funds safe?
They carry lower risk than pure equity funds, but they are not 100% safe. Market drops, interest rate hikes, and credit defaults can cause short-term losses in NAV.
How are equity savings funds taxed?
Eligible schemes receive equity taxation. Long-term capital gains (held over 12 months) are taxed at 12.5% on gains exceeding ₹1.25 lakh per financial year. Short-term gains (held 12 months or less) face a 20% flat tax.
What is the minimum holding period for long-term taxation?
You must hold your units for more than 12 months to qualify for long-term capital gains tax rates.
Can equity savings funds give negative returns?
Yes. Sharp stock market crashes or defaults in debt holdings can push returns into negative territory over short holding periods.
Who should invest in equity savings funds?
They suit conservative and moderate investors with a 2 to 4-year time frame seeking tax-efficient returns and lower volatility.
An equity savings mutual fund is a professionally managed collective investment scheme that aims to provide capital appreciation and regular income while keeping downside volatility lower than pure stock funds.
Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is published solely for educational purposes and does not constitute direct investment or tax advice. Capital gains tax rules and SEBI regulations are subject to change.
ABOUT THE AUTHOR

