
PM Mudra Yojana 2026: Scheme, Loan Eligibility, and how to apply online
Starting or scaling a micro-business requires capital, but traditional loans are often inaccessible due to stringent collateral demands. The Pradhan Mantri Mudra Yojana (PMMY) resolves this by offering collateral-free institutional credit up to ₹20 lakh—recently increased from ₹10 lakh via the new Tarun Plus category exclusively for income-generating activities. Whether you are exploring the latest mudra yojana loan eligibility, navigating the mudra loan online apply process, locating the official pradhan mantri mudra yojana application form, or executing a jansamarth mudra loan application, this comprehensive guide outlines everything required to secure funding. Forecast your debt obligations beforehand using the Business Loan EMI Calculator at RupeeMoney.
What Is PM Mudra Yojana 2026?
The pradhan mantri mudra yojana pmmy is a flagship Government of India initiative introduced to democratize financial access for small and micro enterprises. The core mandate of this mudra yojana scheme is to fund non-corporate, non-farm income-generating commercial operations.
These pm mudra loan disbursements do not come directly from the government. Instead, they are sanctioned and managed through a vast domestic network of participating lending institutions, including commercial banks, Small Finance Banks, Non-Banking Financial Companies (NBFCs), and Microfinance Institutions (MFIs).
The scheme systematically targets businesses engaged in:
- Manufacturing and production
- Wholesale and retail trading
- Professional and local services
- Select agriculture-allied commercial activities (like commercial dairy, poultry, and localized beekeeping)
The pradhanmantri mudra yojana loan framework is structured around four financial tiers: Shishu, Kishor, Tarun, and the newly established Tarun Plus. While the absolute loan ceiling under the scheme is now ₹20 lakh, the exact capital a founder receives depends on their operational stage, sector, historical repayment discipline, and the underwriter’s independent risk assessment.
What Is the Mudra Yojana Loan Eligibility?
The foundational mudra yojana loan eligibility parameters are heavily skewed toward individuals and micro-businesses that require immediate credit for legitimate, income-generating commercial activities. PMMY explicitly prohibits the use of these funds for personal consumption, real estate speculation, or non-commercial asset creation.
Any Indian citizen possessing a well-documented, commercially viable business plan for a micro-enterprise can approach an authorized financial institution to apply. The business entity can be a sole proprietorship, a registered partnership firm, a Limited Liability Partnership (LLP), or a private limited company, provided it fits the micro-business definitions. For detailed strategies on selecting the most loan-friendly business structure, founders can consult the comprehensive guides on the RupeeMoney Blog.
Basic eligibility checkpoints include:
- Legal standing: The applicant must possess a clear financial record and qualify under the specific lending institution’s internal KYC and credit policies.
- Commercial viability: The applicant must present a structured, mathematically sound business plan proving that the venture will generate sufficient cash flow.
- Purpose of credit: The requested capital must be strictly earmarked for income generation, inventory procurement, working capital, or asset acquisition for the business.
- Sectoral alignment: The business must operate within the designated eligible sectors (manufacturing, trading, services, or agriculture-allied).
- Tarun Plus prerequisite: To unlock the ₹10 lakh to ₹20 lakh bracket, the borrower must have a verified history of successfully securing and entirely repaying a previous Tarun-category loan without defaults.
Who Should Consider a PM Mudra Loan?
This financial scheme is custom-built for grassroots commercial operations. The target demographic includes:
- Local grocery stores, pharmacies, and small retail outlets
- Automobile, electronics, and machinery repair workshops
- Dhabas, cloud kitchens, cafes, and local bakeries
- Small-scale manufacturing units, lathe machine operators, and textile assemblers
- Independent artisans, traditional craftspeople, and weavers
- Salons, tailoring boutiques, and dry-cleaning services
- Commercial transport operators (auto-rickshaws, small goods carriers, taxis)
- Agro-processing, food packaging, and commercial dairy units
How Much Loan Can You Get Under PM Mudra Yojana?
The PM Mudra Yojana intelligently segments its capital distribution into four distinct categories, ensuring that the financial product matches the precise operational lifecycle of the business.
| Loan Category | Loan Amount Ceiling | Primary Business Purpose |
| Shishu | Up to ₹50,000 | Very small, conceptual, or early-stage micro-business requirements |
| Kishor | Above ₹50,000 to ₹5 lakh | Stabilizing operations, boosting inventory, and securing daily working capital |
| Tarun | Above ₹5 lakh to ₹10 lakh | Business expansion, heavy equipment purchase, and facility upgrades |
| Tarun Plus | Above ₹10 lakh to ₹20 lakh | Aggressive expansion for proven borrowers with a successful Tarun repayment history |
It is crucial to understand that the ₹20 lakh maximum ceiling is heavily conditional. The Tarun Plus tier acts as a reward mechanism for disciplined financial behavior, permanently locked away from first-time PMMY applicants.
Deep Dive: The Different Types of Mudra Loans
Understanding the nuances of each category ensures that you apply for the correct financial product, significantly lowering your chances of application rejection.
Shishu Mudra Loan
The Shishu category encompasses micro-loans capped at ₹50,000. It is engineered for the earliest stages of a business lifecycle. This could be an individual setting up a roadside vegetable stall, buying basic tools for a home-based tailoring service, or acquiring initial inventory for a small pushcart business. If you are researching the shishu mudra loan online apply process, you will find that these applications face the lowest barriers to entry. They can be quickly initiated via digital lending routes, subject to the applicant possessing a clean basic credit history and clear intent.
Kishor Mudra Loan
The Kishor Mudra loan bridges the gap between ₹50,000 and ₹5 lakh. This is the most active category for operational businesses that have already established product-market fit but require an immediate capital injection to stabilize. A functioning retail shop might utilize Kishor funds to stock up heavily before a major festival season, while a local IT repair business might use it to lease a larger commercial space.
Tarun Mudra Loan
The tarun mudra loan caters to advanced credit requirements ranging from ₹5 lakh to ₹10 lakh. This is serious growth capital. Businesses applying here are no longer in the stabilization phase; they are looking to capture market share, purchase expensive specialized machinery, or open secondary branches. Lenders rigorously scrutinize Tarun applications, requiring airtight financial projections, robust historical bank statements, and clear proof of future repayment capacity.
Tarun Plus Loan
Introduced in October 2024 to accommodate the effects of inflation and the rising costs of doing business, Tarun Plus pushes the maximum limit to ₹20 lakh. This category requires absolute financial discipline. A new applicant cannot request ₹20 lakh on day one. They must have previously borrowed under the standard Tarun category (₹5L – ₹10L) and flawlessly closed that loan account. This category serves as expansion capital for the most successful and reliable micro-enterprises in the PMMY ecosystem.
How to Apply for Mudra Loan Online?
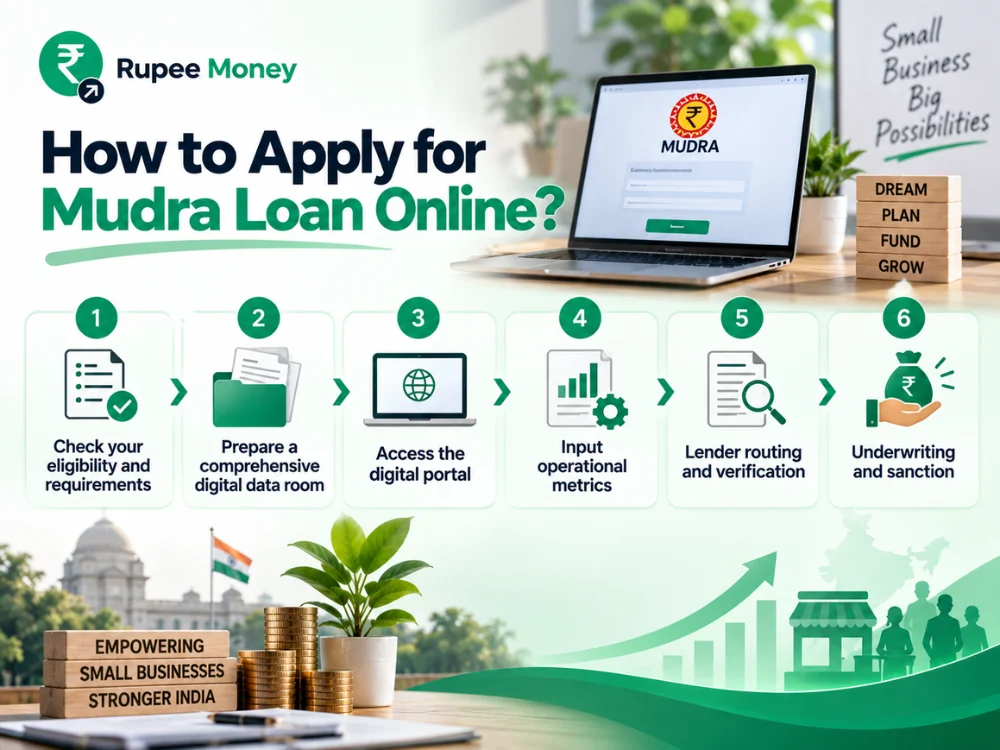
Understanding the exact mudra loan how to apply sequence will save you weeks of administrative delays. Today, the most streamlined digital route is the government-backed JanSamarth portal, designed to centralize and accelerate credit-linked schemes.
Step 1: Check your eligibility and requirements
Before filling out a single form, calculate your exact capital requirement. Over-borrowing leads to EMI defaults, while under-borrowing starves your business. Match your calculated need with the correct PMMY category (Shishu, Kishor, Tarun, or Tarun Plus).
Step 2: Prepare a comprehensive digital data room
Organize high-resolution, self-attested digital copies of your KYC documents, business registration certificates, GST filings, and the last 12 months of business bank statements.
Step 3: Access the digital portal
Initiate the pradhan mantri mudra yojana online apply sequence by navigating to the official JanSamarth portal, or access the dedicated Mudra loan section on your primary business bank’s official website.
Step 4: Input operational metrics
Accurately enter the requested data regarding your enterprise’s vintage, historical revenue, existing liabilities, and exact funding requirement. Ensure this data matches your uploaded bank statements perfectly.
Step 5: Lender routing and verification
The digital system routes your mudra loan application to a suitable lending institution based on your geographic location and profile. The assigned bank will likely initiate a physical field verification of your commercial premises to confirm your operational status.
Step 6: Underwriting and sanction
An online application merely digitizes the intake process; it does not guarantee approval. The bank’s credit underwriter will perform a rigorous risk assessment. If your cash flows justify the EMI, the loan is formally sanctioned.
How to Apply for PM Mudra Yojana Through JanSamarth?
For founders targeting a jansamarth mudra loan, this unified portal provides a heavily guided, step-by-step application journey.
- Navigate to the official JanSamarth portal (ensure the URL is the authentic government domain).
- Register your profile using a mobile number linked to your Aadhaar.
- Select the “Business Activity Loan” category from the primary dashboard.
- Answer the preliminary questionnaire regarding your business structure, gender, social category, and location to establish basic scheme eligibility.
- Input the exact capital amount required.
- Upload the necessary supporting documents, including your detailed project report (for Kishor and Tarun tiers).
- Submit the application. The portal will match you with integrated banks, allowing you to track the real-time status of your file as it moves through the lender’s underwriting queue.
Remember, JanSamarth is an aggregation and routing technology. The final financial risk is borne by the commercial bank, meaning the ultimate power of approval or rejection lies entirely with the bank manager, not the portal.
What Is the Pradhan Mantri Mudra Yojana Application Form?
The official pradhan mantri mudra yojana application form is a standardized data-collection instrument. It provides the bank with the quantitative and qualitative data necessary to underwrite your commercial risk.
To ensure a frictionless process, you must meticulously fill out:
- Applicant Identification: Full legal names, dates of birth, social categories, and residential details of all proprietors/partners.
- Enterprise Details: Registered business name, commercial address, date of commencement, and exact nature of the trade or manufacturing process.
- Financial Request: Desired loan category (Shishu, Kishor, Tarun, Tarun Plus), the precise loan amount required, and the specific end-use (e.g., ₹4 lakh for a new CNC machine, ₹1 lakh for working capital).
- Banking History: Details of existing current accounts, savings accounts, and declarations of any active business or personal loans.
- Performance Metrics: For existing businesses, historical sales data, profit margins, and detailed future financial projections.
Because local bank branches occasionally utilize slightly modified versions of this form based on their core banking software, always download the form directly from your chosen lender’s official website rather than relying on generic internet templates.
What Documents Are Required for a Mudra Loan?
Documentation stringency scales aggressively with the loan size. While a Shishu loan requires basic identification, a Tarun Plus loan demands institutional-grade financial reporting.
Standard Identity and Address Documents
- Government-issued photo identification
- PAN card (mandatory for larger business transactions and higher loan tiers)
- Valid residential and commercial address proof (recent utility bills, registered rent agreements, or property tax receipts)
- Passport-size photographs of the applicants
Commercial Business Documents
- Formal business registration certificates (Udyam Registration is highly recommended)
- Shop & Establishment Act licenses (Gumasta license)
- Industry-specific clearances (e.g., FSSAI license for food businesses)
- GST registration certificates and recent GST return filings (where applicable based on turnover)
Comprehensive Financial Documents
- 6 to 12 months of consecutive business bank statements demonstrating healthy cash flow.
- Income Tax Returns (ITR) of the business and the proprietors for the last 2-3 years.
- Audited or CA-certified provisional financial statements (Profit & Loss Account, Balance Sheet).
- A formal statement of existing financial liabilities and active EMIs.
Project Reports and Business Plans
Particularly for the tarun mudra loan, lenders require a written business plan outlining the target market, competitor analysis, specific equipment quotations from authorized vendors, and a projected cash flow statement proving the business will generate enough surplus revenue to cover the new EMI.
Ensure your financial profile is flawless before approaching the bank. Utilize the resources available at the RupeeMoney homepage to master business financial planning.
The Complete Mudra Loan Application Journey
Securing a pm mudra loan involves navigating a multi-stage banking process. Knowing what happens behind the scenes helps founders prepare accordingly.
- Submission: The borrower submits the completed application form and the full documentary suite either digitally or at the bank branch.
- Initial Scrutiny: The bank’s credit processing team verifies the authenticity of the KYC and business documents.
- Field Investigation (FI): An authorized bank representative visits the commercial premises to verify operations, assess inventory levels, and confirm the business physically exists as claimed.
- Credit Bureau Pull: The underwriter pulls commercial (CRIF/CIBIL MSME) and personal credit reports to check for historical defaults, write-offs, or late payments.
- Financial Underwriting: The bank calculates the Debt Service Coverage Ratio (DSCR). They assess if the business’s net profit is large enough to absorb the new loan EMI while leaving enough cash for daily operations.
- Sanction: If the risk parameters are acceptable, a formal Sanction Letter is issued outlining the approved amount, interest rate, and tenure.
- Legal Documentation: The borrower signs the binding loan agreements, hypothecation deeds, and demand promissory notes.
- Disbursement: Funds are disbursed. Term loans for machinery are typically disbursed directly to the equipment supplier via RTGS, while working capital is credited to the business’s current account.
Can You Apply for a Mudra Loan Without Collateral?
A primary advantage of the pradhan mantri mudra loan apply process is the strict mandate for collateral-free credit. The Government of India enforces that PMMY loans up to ₹20 lakh are explicitly unsecured. Banks are not permitted to ask for residential property, commercial real estate, or gold as collateral.
To protect the banks from catastrophic losses, the government backs these unsecured loans through the Credit Guarantee Fund for Micro Units (CGFMU).
However, founders must understand a critical financial reality: “Collateral-free” does not mean “guaranteed approval.” Because the bank has no physical asset to seize in the event of a default, their underwriting standards regarding your cash flow, credit score, and business viability are exceptionally strict. They will rely entirely on your financial data to gauge risk. Furthermore, assets purchased using the Mudra loan (like machinery or vehicles) are hypothecated to the bank until the loan is fully repaid.
Important Things to Know Before Applying
Before you lock yourself into a multi-year debt contract, keep these operational realities in focus:
- The limit is a ceiling, not a baseline: You will only be sanctioned the amount your business mathematically justifies. Requesting ₹10 lakh when your turnover is ₹2 lakh will result in instant rejection.
- Avoid unofficial agents: The application process is free. Never pay upfront fees to middlemen guaranteeing loan approval.
- Maintain flawless banking hygiene: Route all business income through your current account. Cash transactions hidden from your bank statements cannot be used to prove your repayment capacity to the underwriter.
- Monitor regulatory updates: Government schemes frequently update their compliance requirements. Always verify the latest guidelines directly through official channels before applying.
Conclusion
The PM Mudra Yojana 2026 remains an indispensable financial lifeline for India’s massive micro-enterprise sector. The recent policy upgrade increasing the maximum limit to ₹20 lakh via the Tarun Plus category is a strategic move that rewards disciplined financial behavior, providing proven founders with the heavy capital required to scale aggressively.
However, access to this capital requires professional-grade financial management. Founders must discard the mindset that government-backed schemes require less rigorous business planning than standard commercial loans. Ensure your business structure is legally sound, your financial data room is impeccably organized, and your cash flow projections are realistic. Utilize the analytical tools on RupeeMoney to pressure-test your repayment capacity, choose the loan category that perfectly aligns with your operational reality, and execute your growth strategy with precision.
Conclusion
The PM Mudra Yojana 2026 remains an indispensable financial lifeline for India’s massive micro-enterprise sector. The recent policy upgrade increasing the maximum limit to ₹20 lakh via the Tarun Plus category is a strategic move that rewards disciplined financial behavior, providing proven founders with the heavy capital required to scale aggressively.
However, access to this capital requires professional-grade financial management. Founders must discard the mindset that government-backed schemes require less rigorous business planning than standard commercial loans. Ensure your business structure is legally sound, your financial data room is impeccably organized, and your cash flow projections are realistic. Utilize the analytical tools on RupeeMoney to pressure-test your repayment capacity, choose the loan category that perfectly aligns with your operational reality, and execute your growth strategy with precision.
FAQs
What is PM Mudra Yojana?
The pradhan mantri mudra yojana pmmy is a central government framework designed to facilitate collateral-free institutional credit to eligible small, micro, and non-corporate businesses engaged in income-generating activities.
What is the maximum Mudra loan limit in 2026?
The maximum limit is ₹20 lakh, accessible strictly through the Tarun Plus category for borrowers who have a verified history of successfully repaying a standard Tarun-category loan.
Can I apply for a Mudra loan online?
Yes. The mudra loan online apply sequence can be executed efficiently via the JanSamarth digital platform or directly through the web portals of authorized commercial banks and NBFCs.
What is Shishu Mudra loan?
It is the introductory tier of the PMMY scheme, providing crucial micro-capital up to ₹50,000 for early-stage or highly localized micro-enterprises.
Is Mudra loan a government subsidy?
No. It is a commercial loan product. There is no direct cash grant or blanket subsidy; the borrower is legally bound to repay the principal and accrued interest according to the bank's schedule.
The pradhan mantri mudra yojana pmmy is a central government framework designed to facilitate collateral-free institutional credit to eligible small, micro, and non-corporate businesses engaged in income-generating activities.
Yes. The mudra loan online apply sequence can be executed efficiently via the JanSamarth digital platform or directly through the web portals of authorized commercial banks and NBFCs.
No. It is a commercial loan product. There is no direct cash grant or blanket subsidy; the borrower is legally bound to repay the principal and accrued interest according to the bank’s schedule.
Disclaimer: This comprehensive guide is intended for educational and informational purposes exclusively. PMMY eligibility parameters, bank lending conditions, applicable interest rates, documentation checklists, and online application protocols vary significantly by lending institution and are subject to continuous updates by the Government of India and the Reserve Bank of India. Fulfilling the basic scheme criteria does not legally guarantee loan sanction. The final lending decision is an autonomous commercial assessment made strictly by the participating financial institution. Readers must verify all contemporary guidelines via official government sources before executing any binding financial agreements.
ABOUT THE AUTHOR

