
Mutual Fund Dividends: Concept, Mechanics, Taxation, and Complete Review
When retail investors hear the word “dividend,” they immediately visualize a successful company distributing a slice of its annual corporate profits directly to its shareholders. However, mutual fund dividends operate under an entirely different mechanical and regulatory framework.
A mutual fund pools capital from thousands of investors and allocates that money across a diversified portfolio of equities, government bonds, and money-market instruments. The income these underlying assets generate forms the distributable surplus. From this surplus, an Asset Management Company (AMC) may declare a payout. Today, the Securities and Exchange Board of India (SEBI) officially classifies this payout as an Income Distribution cum Capital Withdrawal (IDCW).
While retail investors still casually use the term “dividend,” adopting the IDCW terminology helps clarify a critical reality: a mutual fund distribution does not represent an additional, magical return. Whenever a fund pays an IDCW, the scheme’s Net Asset Value (NAV) drops by the exact amount distributed.
This comprehensive guide breaks down the operational mechanics of mutual fund dividends, explains how IDCW impacts your portfolio value, details the taxation rules, and helps you determine whether this payout option aligns with your overall financial planning.
The Core Concept of Mutual Fund Dividends
Mutual fund dividends represent distributions that an AMC makes to its unit holders from the scheme’s realized profits or distributable surplus. To eliminate investor confusion, SEBI mandated the renaming of the “Dividend Option” to “Income Distribution cum Capital Withdrawal” (IDCW).
Mutual funds generate the capital required to make these payouts through three primary operational channels:
- Equity Dividends: The fund receives dividend payouts from the individual stocks it holds within its portfolio.
- Fixed-Income Interest: The fund earns regular interest payments from corporate bonds, government securities, and commercial papers.
- Realized Capital Gains: The fund manager actively sells underlying portfolio securities at a profit, locking in realized capital gains.
The AMC does not simply pass every single rupee of earned income directly to investors. The fund manager first deducts scheme expenses, offsets any realized losses, and accounts for other operational adjustments to calculate the final distributable surplus. Crucially, the AMC holds no legal obligation to declare a distribution. The payout frequency and amount depend entirely on market conditions and the fund house’s internal policies.
Operational Mechanics Behind Dividend Payouts
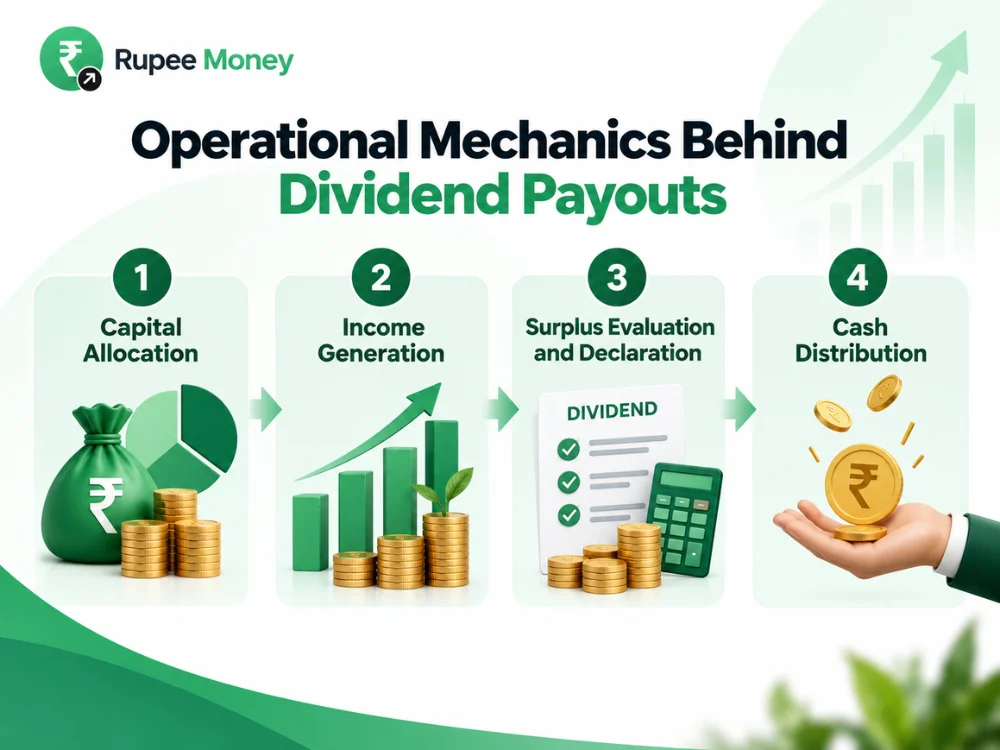
Understanding the exact flow of money clarifies why mutual fund payouts differ so vastly from traditional corporate dividends. You can break down the process into four sequential phases.
Phase 1: Capital Allocation
When you invest your capital, the AMC pools it with funds from other unit holders. The designated fund manager then deploys this massive corpus into various asset classes, strictly adhering to the scheme’s core investment mandate.
Phase 2: Income Generation
The underlying assets actively generate income. Blue-chip stocks deposit corporate dividends into the mutual fund’s bank account. High-rated corporate bonds yield semi-annual interest. Additionally, the fund manager strategically exits profitable positions, transforming paper profits into realized cash gains.
Phase 3: Surplus Evaluation and Declaration
The AMC evaluates the total accumulated cash pile. The board of trustees assesses the distributable surplus and decides whether the market conditions justify declaring an IDCW payout. They establish a specific “record date.” The fund house guarantees no fixed schedule; it declares payouts strictly at its own discretion.
Phase 4: Cash Distribution
If you hold units in your demat account or folio on the record date, you become eligible for the payout. The AMC transfers the cash directly to your linked bank account. Alternatively, if you selected the reinvestment facility, the fund uses that cash to instantly purchase additional units on your behalf.
Impact on Net Asset Value (NAV)
Grasping the NAV adjustment remains the most critical lesson for any mutual fund investor. An IDCW payout represents a withdrawal from your own invested capital, not a bonus reward.
Consider a practical mathematical scenario. Assume you own 1,000 units of an equity mutual fund, and the current NAV sits at ₹50. Your total investment value equals ₹50,000.
The AMC suddenly declares an IDCW of ₹2 per unit. You receive a cash payout of ₹2,000 (1,000 units × ₹2) directly into your bank account.
Immediately following this distribution, the mutual fund removes that cash from its total Asset Under Management (AUM). Consequently, the NAV drops from ₹50 down to ₹48.
Your new portfolio value equals ₹48,000 (1,000 units × ₹48). When you add the ₹2,000 cash sitting in your bank account, your total wealth remains exactly ₹50,000. The fund house simply moved money from your mutual fund folio into your savings account.
Comparing Growth and IDCW Options
AMCs typically offer two variations of the exact same mutual fund scheme: the Growth option and the IDCW option. Both share the exact same underlying portfolio and fund manager, but they handle generated profits differently.
- Treatment of Profits: The Growth option retains all dividends, interest, and realized gains within the fund, allowing the capital to compound continuously. The IDCW option periodically distributes a portion of these profits back to the investors.
- NAV Trajectory: Because the Growth option retains all earnings, its NAV historically climbs much faster than the IDCW option. The IDCW option’s NAV drops every time the AMC executes a payout.
- Cash Flow Mechanics: The Growth option provides zero interim cash flow; you only realize cash when you manually redeem your units. The IDCW option provides unpredictable, periodic cash injections into your bank account.
To visualize how uninterrupted compounding accelerates wealth creation under the Growth option, investors frequently rely on a robust SIP calculator.
The Mechanics of IDCW Reinvestment
Many investors select the IDCW Reinvestment sub-option. Under this facility, the AMC does not transfer cash to your bank account. Instead, the fund house automatically utilizes the declared payout amount to purchase additional units of the exact same scheme at the newly adjusted, post-payout NAV.
While you acquire more physical units, your overall portfolio value remains mathematically identical to a standard Growth option. Because this process triggers unnecessary tax events without providing actual cash liquidity, most financial planners advise long-term wealth builders to simply choose the standard Growth option instead.
Taxation Rules for IDCW Payouts
The Indian government radically overhauled mutual fund dividend taxation in 2020. Previously, the AMC paid a Dividend Distribution Tax (DDT) before transferring the cash to you, rendering the payout tax-free in your hands. Today, the tax burden falls entirely on the investor.
The Income Tax Department treats all IDCW payouts as standard “Income from Other Sources.” You must add the total payout amount to your annual gross income and pay taxes according to your specific income tax slab rate. If you fall into the 30% tax bracket, you surrender 30% of your mutual fund distribution straight to the government.
Furthermore, if your total IDCW payouts from a single AMC exceed ₹5,000 in a single financial year, the fund house must deduct a 10% Tax Deducted at Source (TDS) before crediting the funds to your account.
Advantages of the IDCW Framework
- Automated Liquidity: The payout provides interim liquidity without requiring you to manually log in and submit a redemption request.
- Psychological Comfort: Conservative investors often experience psychological relief when they see tangible cash entering their bank accounts during volatile market cycles.
- No Capital Gains Tracking: Receiving a payout does not trigger complex capital gains tax calculations; you simply declare it as flat income.
Limitations of the IDCW Framework
- Zero Income Guarantees: AMCs hold no legal obligation to pay out consistently. During prolonged bear markets, a fund may freeze distributions entirely.
- Severe Tax Inefficiency: Taxing payouts at standard slab rates punishes high-income earners. A 30% tax haircut on every payout severely damages long-term portfolio growth.
- Compounding Interruption: Pulling cash out of the market routinely destroys the mathematical magic of compound interest.
- Misleading Performance Metrics: Novice investors frequently mistake a high dividend yield for superior fund management, ignoring the subsequent, permanent drop in the scheme’s NAV.
Choosing the Right Option for Your Goals
Your final selection between Growth and IDCW must align perfectly with your distinct financial objectives.
If you aim to build generational wealth, fund a distant retirement, or save for a child’s higher education, you must select the Growth option. By leaving your capital entirely untouched, you allow compounding to work uninterrupted.
Conversely, if you represent a retiree in a lower tax bracket seeking occasional cash infusions to supplement your pension, the IDCW payout option serves a valid purpose. However, if you require a strictly guaranteed, fixed monthly income to cover essential living expenses, mutual funds cannot serve as your primary tool. You should instead explore fixed-income instruments using an FD calculator.
Conclusion
Mutual fund dividends officially titled Income Distribution cum Capital Withdrawal (IDCW) allow AMCs to distribute realized profits back to their unit holders. While the prospect of receiving regular cash payouts sounds highly appealing, investors must accept the mathematical reality: every payout permanently reduces the scheme’s Net Asset Value.
The IDCW framework provides excellent automated liquidity for investors in lower tax brackets who desire intermittent cash flow. However, because these payouts attract heavy slab-rate taxation and actively interrupt long-term compounding, aggressive wealth builders must firmly stick to the Growth option. Ultimately, aligning your mutual fund selection with your precise cash flow requirements and tax liabilities guarantees a smoother, more predictable investment journey.
FAQs
What is IDCW in mutual funds?
IDCW stands for Income Distribution cum Capital Withdrawal. It serves as the new official regulatory terminology for what retail investors traditionally called the "dividend option." The updated name accurately reflects that the AMC distributes both generated income and a portion of your own invested capital back to you.
How does an IDCW payout affect the mutual fund's NAV?
Whenever an Asset Management Company declares a payout, the scheme's Net Asset Value (NAV) instantly decreases by the exact amount distributed. If a fund trades at a ₹100 NAV and distributes ₹5 to its investors, the new NAV immediately adjusts downward to ₹95 to reflect the cash leaving the fund's total asset pool.
Are mutual fund dividends guaranteed or fixed?
No, mutual fund payouts carry zero guarantees. The fund manager and the board of trustees decide whether to declare a distribution based entirely on the availability of a distributable surplus and prevailing market conditions. A fund may pay handsomely during a bull market and freeze distributions completely during a recession.
How does the taxation of mutual fund dividends work in India?
The Income Tax Department treats all IDCW payouts as regular income. You must add the entire payout amount to your gross annual income and pay taxes according to your specific tax slab. Additionally, if your total payouts from a single fund house exceed ₹5,000 in a financial year, the AMC deducts a 10% Tax Deducted at Source (TDS) before transferring the cash to your bank account.
Why should long-term investors avoid the IDCW reinvestment option?
The IDCW reinvestment option declares a taxable payout but automatically uses that cash to buy more units rather than transferring it to your bank account. This forces you to pay taxes on the distribution without actually receiving any liquid cash. Long-term investors looking to accumulate wealth should simply choose the Growth option to defer taxes and maximize compound interest.
When should an investor actively choose the IDCW payout option?
Investors should select the IDCW payout option only if they require intermittent, unpredictable cash flow and fall into lower income tax brackets. Retirees who want their portfolios to occasionally generate liquid cash without forcing them to manually sell units often utilize this specific facility.
IDCW stands for Income Distribution cum Capital Withdrawal. It serves as the new official regulatory terminology for what retail investors traditionally called the “dividend option.” The updated name accurately reflects that the AMC distributes both generated income and a portion of your own invested capital back to you.
Whenever an Asset Management Company declares a payout, the scheme’s Net Asset Value (NAV) instantly decreases by the exact amount distributed. If a fund trades at a ₹100 NAV and distributes ₹5 to its investors, the new NAV immediately adjusts downward to ₹95 to reflect the cash leaving the fund’s total asset pool.
Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. The information, taxation data, and operational mechanics presented in this article are compiled strictly for educational and informational awareness. RupeeMoney does not operate as a SEBI-registered Investment Adviser. Nothing published here constitutes formal investment, tax, or legal counsel. IDCW distributions carry no guarantees. Investors must independently evaluate their risk tolerance and consult a certified financial planner prior to making capital allocations.
ABOUT THE AUTHOR

