
Top Wealth Management Companies in India – Which One Is Right For You
Managing substantial wealth requires much more than simply picking winning stocks or buying mutual funds. As your personal assets expand, you face multifaceted challenges. You need to structure custom portfolios, minimize tax liabilities, plan your estate, and protect your capital from market drawdowns. This is where professional Wealth Management becomes essential. Welcome to RupeeMoney, your dedicated guide for smart investing, wealth creation, and financial security.
India’s economic growth is creating a massive population of affluent and High-Net-Worth Individuals (HNIs). In response, banks, dedicated private wealth firms, and independent advisory boutiques now offer specialized investment management services.
However, you should never pick a firm based purely on a prestigious brand name or the size of its assets under management. Choosing among the top wealth management companies in India requires a deep analysis of fee structures, regulatory registrations, investment philosophies, and potential conflicts of interest.
In this comprehensive guide, we explain how modern wealth firms operate, break down the list of wealth management companies, and help you evaluate the best wealth management firms for your unique financial goals.
Wealth Management Explained: Meaning, Process & Benefits
Wealth Management is a high-level, consultative financial service. It combines investment management, comprehensive financial planning, tax structuring, and estate governance into a single coordinated strategy for affluent individuals and families.
Unlike a traditional stockbroker who focuses solely on executing individual buy or sell orders, a wealth manager evaluates your entire balance sheet. They align every investment with your personal risk tolerance, family milestones, and liquidity requirements.
THE WEALTH MANAGEMENT ECOSYSTEM
| Investment & Asset Allocation | Direct Equity, Debt, PMS, AIFs, Global |
| Financial & Succession Planning | Estate Planning, Trusts, Will Drafting |
| Risk Mitigation & Preservation | Insurance, Hedging, Liquidity Management |
| Tax & Regulatory Optimization | Tax-Loss Harvesting, Corporate Structures| |
What Does Wealth Management Include?
Depending on the institution you hire, wealth management services typically encompass:
- Custom Portfolio Management: Constructing bespoke portfolios tailored to your financial goals.
- Comprehensive Financial Planning: Building long-term roadmaps for retirement, lifestyle funding, and building wealth in your 20s and beyond.
- Tax Strategy: Structuring investments to reduce long-term capital gains taxes legitimately.
- Estate and Succession Planning: Setting up private family trusts and drafting wills to pass assets to future generations smoothly.
- Alternative Investment Access: Accessing venture capital, private equity, and Specialized Investment Funds (SIF).
- Risk Management: Protecting assets against liability, economic shocks, and inflation.
Wealth Management for Affluent Investors: Key Benefits
As your wealth compounds, managing your personal balance sheet becomes a full-time job. You might hold direct equities, fixed deposits, commercial real estate, startup angel investments, and family business equity.
A dedicated wealth manager consolidates these fragmented pieces into a single, unified dashboard. They ensure that every asset works toward your overarching life goals rather than operating in isolation.
How Do the Best Wealth Management Firms Operate?
Professional wealth management firms follow a disciplined, five-step advisory cycle to deliver consistent client outcomes:
Discovery & Profiling → Strategic Asset Allocation → Execution & Deployment → Continuous Monitoring → Dynamic Rebalancing
- Discovery and Profiling: The wealth manager thoroughly analyzes your income, existing assets, liabilities, tax bracket, and risk appetite.
- Strategic Asset Allocation: The firm drafts an Investment Policy Statement (IPS). This document sets target percentages for equities, fixed income, real estate, and alternatives.
- Execution and Deployment: The firm deploys your capital through direct equities, bonds, mutual funds, Portfolio Management Services (PMS), or Alternative Investment Funds (AIFs).
- Continuous Monitoring: The manager tracks portfolio performance daily and delivers consolidated monthly statements.
- Dynamic Rebalancing: When market swings push your equity allocation above target limits, the manager rebalances your portfolio to lock in gains and manage risk.
Professional Wealth Management Services in India: Who Can Benefit?
Wealth management is not a one-size-fits-all solution. Retail investors starting their journeys can easily manage their finances using index funds and disciplined financial planning.
However, you should consider hiring the best wealth management firms when you:
- Accumulate investable liquid assets exceeding ₹50 lakh to ₹1 crore.
- Own complex, illiquid assets like private business shares or multiple commercial properties.
- Require sophisticated estate planning to transfer wealth across generations.
- Need access to institutional-grade products like private credit, pre-IPO shares, and offshore funds.
- Lack the time or technical expertise to manage portfolio risks actively.
Top Wealth Management Companies in India: Complete List
The Indian wealth ecosystem features a vibrant mix of private banking divisions, standalone non-banking wealth managers, and specialized boutique multi-family offices.
Here is a prominent list of wealth management companies currently operating in the Indian financial market:
| Wealth Management Firm | Primary Service Model | Target Market Focus |
| 360 ONE Wealth (formerly IIFL Wealth) | Independent Wealth & Asset Management | High-Net-Worth & Ultra-HNIs / Family Offices |
| Kotak Private Banking | Bank-led Integrated Private Banking | Ultra-HNIs, Business Promoters & Entrepreneurs |
| Nuvama Wealth (formerly Edelweiss) | Comprehensive Wealth Management & Advisory | Affluent, HNIs, and Corporate Treasuries |
| ICICI Bank Private Banking | Universal Bank Wealth Division | Affluent Professionals & Emerging HNIs |
| HDFC Bank Private Banking | Universal Bank Wealth Division | HNIs, Conglomerate Owners & NRIs |
| Axis Bank Private Banking (Burgundy Private) | Bank-led Private Wealth Platform | Affluent Individuals & Business Families |
| Anand Rathi Wealth | Strategy-Driven Retail & HNI Wealth | Emerging HNIs and Business Owners |
| Motilal Oswal Private Wealth | Equity-Centric Wealth Management | Equity-Oriented HNIs and Family Offices |
| Aditya Birla Capital Private Wealth | Conglomerate Financial Services | Multi-Asset HNIs and Corporate Clients |
Note: This list represents prominent industry participants. Always evaluate each firm against your personal investment criteria before signing any advisory contract.
Best Wealth Management Firms: Key Factors to Compare
Never choose a wealth manager based solely on glossy presentations or family recommendations. Use these critical parameters to evaluate competing firms:
WEALTH FIRM EVALUATION PILLARs
LEGAL REGULATION FEE STRUCTURES PRODUCT RANGE
• SEBI RIA vs PMS/AIF • Fixed Fee vs % AUM • Open Architecture
• Fiduciary Standard • Hidden Product Comm. • Proprietary Push
How Is the Firm Regulated Under SEBI?
Regulatory registration defines the legal standard of care a firm owes you:
- SEBI Registered Investment Advisers (RIA): These advisors charge you a direct fee and operate under a strict fiduciary standard. They cannot earn backdoor product commissions, ensuring unbiased advice.
- Portfolio Managers (PMS): SEBI regulates these entities under PMS regulations. They directly manage your demat account using discretionary or non-discretionary mandates.
- Brokers and Distributors: These entities distribute third-party products and earn commissions from asset managers.
Always verify the entity’s registration status directly on the official SEBI portal before transferring any capital.
How Do Wealth Management Fees and Commission Models Work?
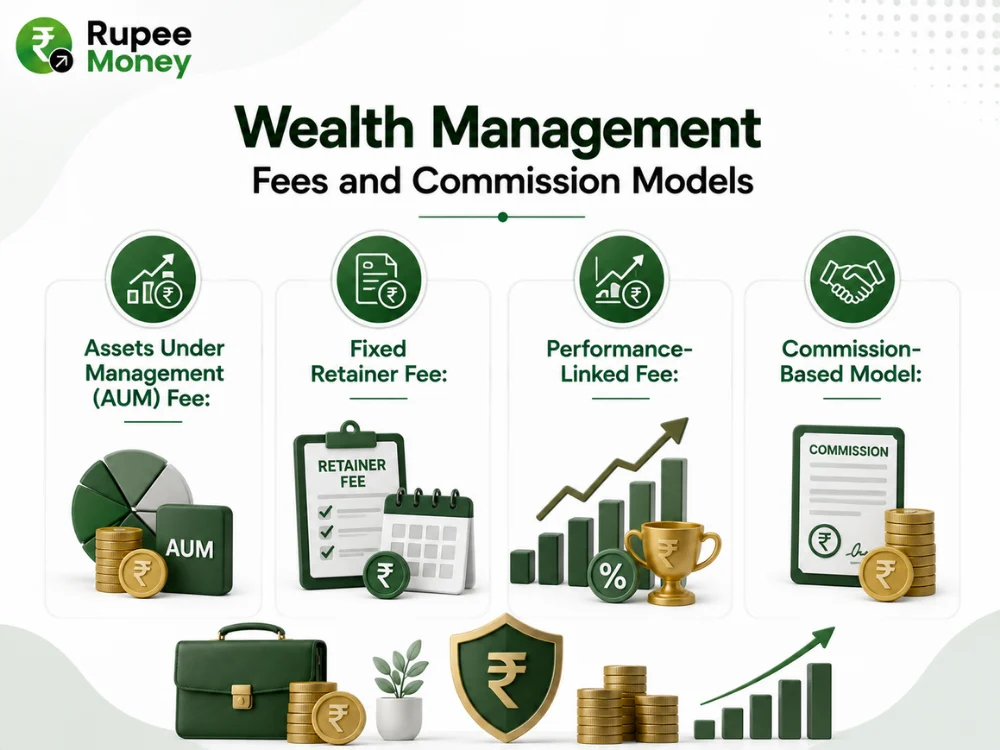
Fees erode compounding returns over time. Different wealth management companies deploy distinct pricing models:
- Assets Under Management (AUM) Fee: The firm charges a flat percentage (usually 0.50% to 1.50% annually) of the total capital they manage for you.
- Fixed Retainer Fee: You pay a flat quarterly or annual fee for holistic advice, irrespective of your portfolio size.
- Performance-Linked Fee: The firm takes a base fee plus a percentage of profits (often 10% to 20%) generated above a specific hurdle rate (e.g., 10% annual return).
- Commission-Based Model: The advisor claims to offer “free” services but earns heavy distribution commissions from mutual funds, PMS, and structured debt issuers.
Always request a comprehensive, written fee schedule that outlines all direct and indirect charges.
Investment Products That Wealth Managers Offer?
Top firms practice Open Architecture. This means they recommend the best investment products across the entire market, regardless of which institution manufactures them.
Conversely, some firms practice Closed Architecture. They aggressively push their own in-house mutual funds, structured notes, and lending products. Make sure your wealth manager offers access to:
- Direct equities and top-tier large cap mutual funds.
- Sovereign and corporate fixed-income bonds.
- Specialized Category I, II, and III Alternative Investment Funds (AIFs).
- Global equity and offshore feeder funds.
Why Does Investment Philosophy Matter?
Every wealth firm operates on a foundational investment philosophy:
- Some firms believe in aggressive market-timing and tactical stock picking.
- Other firms prioritize passive indexing, systematic rebalancing, and long-term asset allocation.
Make sure the firm’s core philosophy matches your personal risk profile. If you desire stable capital preservation, partnering with a high-turnover, aggressive equity boutique will create frustration.
Risk Management and Portfolio Diversification by Wealth Managers
True wealth management focuses primarily on risk mitigation rather than chasing maximum returns. Wealth managers defend your portfolio against multiple threats:
| TYPE OF RISK | WEALTH MANAGER’S MITIGATION STRATEGY |
| Market Drawdown | Dynamic rebalancing into fixed income and gold |
| Concentration | Strict exposure caps on single stocks and sectors (≤ 10%) |
| Interest Rate | Matching bond duration with your personal cash-flow needs |
| Liquidity Shock | Maintaining an emergency pool in liquid debt funds |
By enforcing strict portfolio diversification, a wealth manager prevents a single corporate default or sector collapse from devastating your family’s net worth.
What Conflicts of Interest Should You Watch For?
Conflicts of interest represent the biggest hidden danger in wealth management. Watch out for these red flags:
- Proprietary Product Pushing: If your private banker constantly recommends their own firm’s PMS or insurance products, they are likely maximizing corporate revenue rather than serving your best interests.
- High Portfolio Turnover (Churning): If your manager frequently buys and sells securities, they may be churning your account to generate trading brokerage fees.
- Opaque Structured Notes: Some firms earn massive upfront distribution payouts (up to 4% to 5%) by selling complex structured derivatives to unsuspecting clients.
Insist on full transparency regarding every commission and trail fee your wealth manager earns from your account.
Difference Between Wealth Management and Portfolio Management
Investors often use these terms interchangeably, but they represent very different scopes of service:
| Feature | Portfolio Management Services (PMS) | Holistic Wealth Management |
| Core Focus | Pure investment execution in stocks/bonds | Complete personal balance sheet management |
| Scope of Service | Stock selection and market performance | Investments, tax planning, estate, and trusts |
| Delivery Model | Dedicated investment strategy mandate | Integrated advisory and lifestyle planning |
| Client Interaction | Performance factsheets and quarterly calls | Dedicated relationship managers and family meetings |
| Regulation | Governed under SEBI (PMS) Regulations | Governed under SEBI RIA, PMS, and AIF frameworks |
Top Wealth Management Companies in India: A Beginner’s Selection Guide
If you are hiring a wealth manager for the first time, follow this step-by-step evaluation framework:
Step 1: Calculate your total liquid net worth and identify your required services.
Step 2: Shortlist 3 to 4 firms from the list of wealth management companies.
Step 3: Verify SEBI registration credentials and check regulatory track records.
Step 4: Interview the designated Relationship Manager (RM) and evaluate their experience.
Step 5: Demand a detailed, transparent breakdown of all advisory fees and commissions.
Step 6: Review sample portfolio reports, client dashboards, and risk monitoring tools.
Top Wealth Management Companies in India: Comparison Checklist
Use this actionable checklist when interviewing competing wealth management firms:
- Does the firm hold valid SEBI registrations for the specific services offered?
- Does the advisor operate under a fiduciary model with transparent fee disclosures?
- Does the firm offer an open-architecture platform with zero proprietary bias?
- What is the total all-in annual cost (management fees + commissions + custody charges)?
- Who will manage my day-to-day relationship, and what is their professional background?
- How frequently will I receive consolidated performance and tax reports?
- What are the exact account closure procedures, exit loads, and transfer terms?
Conclusion
Navigating the top wealth management companies in India requires looking far beyond marketing slogans and brand prestige. A truly great wealth management firm acts as your trusted fiduciary partner. They preserve your capital, optimize your taxes, and guide your family across generational wealth milestones.
When reviewing any list of wealth management companies, prioritize transparency above all else. Choose firms that disclose all fee structures openly, enforce strict fiduciary standards, and offer an open-architecture platform free of proprietary bias.
Take your time to interview prospective managers, analyze their risk management processes, and select a partner who understands your vision for the future. Explore more financial planning guides and investment strategies on RupeeMoney to manage your wealth with confidence and clarity.
FAQs
What is Wealth Management?
Wealth Management is an all-inclusive financial discipline that integrates investment management, financial planning, tax optimization, risk mitigation, and estate planning into a single strategy for affluent individuals and families.
Which are the top wealth management companies in India?
Prominent industry leaders include 360 ONE Wealth, Kotak Private Banking, Nuvama Wealth, ICICI Bank Private Banking, HDFC Bank Private Banking, and Axis Bank Private Banking.
What are the best wealth management firms for HNIs?
The best wealth management firms depend on your individual requirements. If you seek pure investment performance and open architecture, specialized independent firms like 360 ONE or Nuvama excel. If you need seamless corporate banking, lending, and forex solutions alongside investments, bank-led private wealth platforms like Kotak or ICICI provide superior convenience.
How do wealth management companies make money?
Wealth management companies earn revenue through advisory fees, assets under management (AUM) percentages, performance-linked profit shares, and product distribution commissions paid by asset managers.
Is wealth management risk-free?
No. Wealth management services do not eliminate market volatility or credit defaults. Underlying investments remain subject to market movements. However, professional wealth managers mitigate these risks through disciplined asset allocation and portfolio diversification.
Wealth Management is an all-inclusive financial discipline that integrates investment management, financial planning, tax optimization, risk mitigation, and estate planning into a single strategy for affluent individuals and families.
The best wealth management firms depend on your individual requirements. If you seek pure investment performance and open architecture, specialized independent firms like 360 ONE or Nuvama excel. If you need seamless corporate banking, lending, and forex solutions alongside investments, bank-led private wealth platforms like Kotak or ICICI provide superior convenience.
Disclaimer: This article is published solely for educational and informational purposes and does not constitute formal financial, tax, legal, or investment advice. Wealth management services and market-linked securities involve financial risk, including the possible loss of principal capital. Always verify SEBI registration credentials and consult a certified financial planner or tax advisor before signing advisory agreements.
ABOUT THE AUTHOR

